Qard Al-Hassan - Benevolent Lending

WHAT IS QARD AL-HASSAN?
Qard al-hassan, also known as qard al-hasan, is an Islamic finance term that essentially refers to a loan that is interest free. Typically in a transaction that includes qard al-hassan, the borrower will repay the amount owing under the principal amount without any other mark up or interest payment being charged. Qard al-hassan financial products are compliant with Sharia rules that dictate that interest (riba) payments are not permissible, whether the interest is being paid or being charged.
These types of loans offer financial solutions for Muslims looking to borrow funds that do not include any interest payments.
Qard al-hassan loans are loans that are provided to help others. The word hassan itself means acceptable or good (of good faith). Islamic banking services are now offering qard al-hassan loans for both Muslims and non-Muslims.
Qard Al-Hassan Loans
In Islam and Islamic banking, Qard al-hasan loans do not have an interest rate element, and this means that businesses and consumers are able to borrow money on a goodwill basis. Generally speaking, qard al-hasan loans tend to be used for welfare purposes. The Quran stipulates that Muslims should endeavour to provide these types of benevolent loans where possible and to those who need these kinds of services.
"Establish regular prayer and give regular charity and give Allah Qard Hassan" (Quran 73:20)
The principle of qard al-hassan in Islam enables Muslims to further the social justice ethos that underpins Islamic finance. Islamic finance facilitates loans from those with the funds to those who need financial assistance without breaching Sharia rules. Qard al-hassan can be viewed as a loan agreement that is akin to giving charity. The borrower and lender sign an agreement confirming the terms of the qard.
HOW DOES QARD AL-HASSAN WORK?
In Islam, qard al-hassan works in the following way. A lender will lend a business or service an amount of money that they need (usually for social justice purposes). The principal amount borrowed will be interest-free. The borrower will then repay the amount of money borrowed without any interest or surplus payments owing. Borrowers are permitted to pay an additional amount back to the lender as a gesture of goodwill, but this cannot be done based on any promise or commitment.
Qard al-hassan loans do not increase over time or accumulate any interest charges like traditional loans do. This means they offer problem solving solutions for Muslims.
The most important element of Islamic qard al-hasan loans is that they are untouched by any form of riba. There should not be any reference or link to the economic market conditions and fluctuations, and the lender cannot ask for the return of the loan before the contractual repayment period ends.
Qard Al-Hassan - The Redistribution Of Wealth
Islamic finance systems focus on socio-economic justice and the enhanced wellbeing of society, especially the alleviation of poverty. Alongside sadaqa and zakat, qard al-hassan is an essential Islamic finance instrument of redistribution of wealth.
Qard al-hassan minimises the cost of borrowing and remains compliant with Islamic Sharia law. It's one of several halal investing principles that guide how Muslims manage and grow wealth ethically.
Social Justice, Qard And The Islamic Finance Economic System
The Islamic finance economic system has always centred on principles of social justice (as mirrored throughout the practices and teachings of Islam). The focus of the finance system is to ensure and improve the overall wellbeing of society and using money to enhance social conditions.
Qard al-hassan is a key concept that acts as a crucial redistributive instrument. The distribution of funds from the rich to the poor aims to reinforce social unity and cooperation. As the global experience of, and appetite for, ethical finance options and factor analysis continues to grow, qard al-hassan is fast emerging as an important tool in the fight against poverty and the drive to ensure there is more financial freedom and equity for poorer communities.
As more and more Islamic finance companies and banks are offering innovative qard al-hassan products and financial services, project management for those customers and business operations working within the social justice sector will become easier and more accessible. Qard al-hassan services will start to become more readily available in banking and private sector financial industries.
The opinion of scholars is that qard al-hassan loans are problem solving as they facilitate the redistribution of funds that are compliant with ethical and Islamic finance principles. Islamic finance is facilitating financial freedom and investment options for those who have historically been excluded from traditional financial markets and industries that did not cater to their religious requirements.
According to Sharia law, qard al-hassan loans are deemed to be acts of good faith, and loans that help those in need. Advancement of news relating to qard products and websites, and information technology means that qard al-hassan financial services are more readily available and searched for online, especially in Middle Eastern territories. This has enhanced the supply and demand of qard services. Historically, qard al-hassan loans have proved to be effective for economic growth, enhancing employment, and alleviating poverty.
Receive insights on ethical financing and Islamic finance directly to your inbox.
Explore more news
The United Kingdom is going through a turbulent financial and economic situation. Coming out of the pandemic, navigating the financial landscape and the economy has resulted in the highest inflation we have seen in decades, alongside stagnant wages and rises in energy bills.
The cost of everything is increasing and it is ordinary people who are struggling. From the National Health Service, to the private sector, and across every community we are all feeling the pinch.
Whilst we expect the government to ensure there is sufficient funding and investment in communities, families, and industries, what is clear is that we all need to be taking steps to minimise the risk of financial losses.
Whilst the government seems more focused on climate action, decarbonisation, and reducing emissions than effective financial planning, as individuals we need to take responsibility for our own actions.
Now is the time for us to be examining out own finances and expenditure.
As we move forward into 2024 and beyond there are some key steps you can take to make sure you are in the best financial position you can be.
Get Informed
Before we move on to the steps we can take to improve our finances, we need to consider our own financial literacy.
As individuals and communities we need to prioritise learning about and understanding finance. Prepare for the future by taking the time to learn about the key principles around money and money management. Learn how interest works, and why it is deemed to be haram in Islam.
As consumers, we need to scrutinise and assess our impact on our finances and understand how we spend and save.
The more information you have the better. The worst thing you can do is bury your head in the sand.
Start by getting details of all your bank accounts, savings, direct debits and debts. Understand your incomings and outgoings and make sure you are living within your means.
One of the key principles of Islam is to live within your means. This encourages people to be mindful of how they consume and spend, and to avoid extravagance.
There are also stringent obligations to ensure that you stay away from riba (interest) and haram spending. You cannot do this properly unless you understand your finances fully.
Knowing your finances means you can avoid haram practices. Also, in order to plan effectively for the future you need to understand how your money is saved, whether it accrues interest, and how much you can save each month.
There is ample information and advice on this website to guide you along the way. In addition, technology is so advanced that these days we can check all our accounts and finances using our mobile phones. As a result, you can keep a close eye on your finances.
Focus On Sustainable And Responsible Consumption And Investing
Focusing on sustainable and responsible consumption is key for everyone, but especially Muslims who want to live in a Sharia compliant way. Islam encourages ethical and socially responsible behaviour in every area of life.
We are required to make a commitment to being sustainable and responsible. Over-consumption goes against Islamic finance principles.
Some of the best ways of achieving a more halal and sustainable level of consumption include:
- The concept of amanah
- Islam considers money and wealth to be an amanah from Allah. What this means is that Muslims act as stewards of the wealth and will be held accountable for how they use and spend it. Sharia rules guide us to use the wealth in morally and ethically sound ways, and Islamic finance provides us with the structure in which to do this. The construction of Islamic finance principles helps us to make sure we operate within Islamic principles when it comes to our finances. In personal terms, it means that we should be more considered and careful with our finances, avoiding excessive spending, and always taking care to mind our money.
- Avoiding waste
- Any kind of waste should be avoided, and this includes wasteful purchases and spending. Responsible consumption aligns with the principle of stewardship. Keep an analysis of what you spend on and how you spend and you will be able to identify and report on poor spending and then eliminate it.
- Avoiding haram but invest wisely
- As Islam prohibits actions that cause harm to others, we need to be mindful of any spending that is deemed to be haram. This includes investing in industries that are haram such as gambling, alcohol and porn industries. Instead, we should look at halal investment options and services.
- There is a huge social impact to investing in haram industries. Be mindful of where your sums are stored and being invested. The corporate world may be focused on profits, but there are socially responsible and Sharia compliant industries you can invest in. There is also increased regulation and protective policy of most investment options across the United Kingdom which means you can be assured that your money will be safe.
Think Long Term
As mentioned above, try and think long-term. When it comes to your finances, whilst it may seem like you are living from one pay day to the next, there are some small steps you can take to plan for the future. As the old saying goes - fail to prepare, prepare to fail.Planning ahead can relieve the pressure you face tomorrow. The market is fluctuating and temperamental now but it will not always be like this.
Planning ahead builds financial stability and means you can cope with emergencies when they arise. Think of the scenario of when you are much older and unable to work as hard.
Living from one pay day to the next can result in more and more people turning to debt and credit to cover their everyday expenses. Long-term financial planning helps break the cycle of debt. The UK has an ageing population, so it is even more important that we plan ahead and make the right financial decision for our future.
Here are some steps you can take to effectively plan ahead:
- Set some financial goals: these do not have to be complicated or difficult. Instead, they should be realistic. For example, one goal could be to start saving for a home.
- Create a budget: once you have a goal, go through all your financial data including incomings and outgoings. Try and track your spending to see where you can cut back and what you can do cheaper. This will help you identify any spare funds for saving. Even £5 a month will help.
- Have an emergency fund: to stop yourself from falling into debt, try your very best to have an emergency fund.
- Save and invest regularly: consistent investing, even with the tiniest amounts, can accumulate over time. When dealing with the increasing cost of living, we need to have some money set aside for emergencies.
- Ditch the debt: overspending is one of the fastest ways to end up in debt. If you are in debt there is help and support out there, so reach out and see if you can reduce your debt and lower your spending.
For Muslims, financial literacy means they can plan and prepare responsibly. It also means they can account for their zakat payments which are obligatory.
Embrace Islamic Finance Principles
Muslims are obliged to follow the Sharia rules relating to finance. For Muslims, true success comes with pleasing Allah.
Embracing Islamic finance principles is extremely important for those wanting to be compliant with Islamic rules relating to financial dealings, but also for those wanting to live and manage their money responsibly.
Islamic finance prohibits any form of interest - that includes payment of interest or receipt of it. The whole idea behind avoiding interest is that this creates a fairer society and does not burden one group more than others. Interest is seen as being rooted in unethical and irresponsible economics.
Islamic finance is based on social justice and fairness. Islam places great emphasis on ethical behaviour, through choice. This means there is an obligation on Muslims to treat all their social and economic dealings with care.
Another key concept from Islamic finance is the idea of profit and loss sharing. Sharia rules encourage profit and loss sharing arrangements. This is to ensure that both parties are treated fairly.
For Muslims looking to save costs and stay away from debt, focusing on Islamic finance rules means they can operate Islamically but also in a way that maximises their money and makes it go further.
Establish Zakat And Sadaqa
Establishing zakat and sadaqa are critically important in Islam. Zakat is an obligation upon all Muslims, whilst sadaqa is voluntary but hugely encouraged.
In order to pay your zakat you need to understand your finances fully. Calculating and paying zakat on an annual basis is essential for Muslims.
Working out your zakat requires an important wealth assessment and analysis calculation. What it means is that through the whole year you are more conscious of your spending and you are making plans for the payment of zakat.
Zakat encourages people to be aware of their financial assets and situation. This prevents the problem of not knowing how much zakat you need to pay.
Understanding the importance of zakat and sadaqa actually encourages savings throughout the year. It also helps people to budget and plan accordingly. Also, by paying zakat people are able to understand the importance of distinguishing between needs and wants in their own lives.
Sadaqa, whilst voluntary, generates a feeling of generosity, compassion and empathy. By willingly sharing our wealth with others it means we are attuned to the needs of others and can budget accordingly.
Stay Away From Debt And Interest
Now is the time to really understand and analyse your spending habits. Make more informed choices about where to spend and save your money. This encourages a more balanced and moderate lifestyle.
Managing your debt is always a good risk management strategy. If you have a credit card then try and stop using it and clear any debt you owe. Credit card debt carries high interest rates and is deemed haram.
Staying away from debt is one of the best financial decisions you can make for yourself. Debt can lead to financial strain, and negatively impacted credit scores. It also means you have overall less disposable income from jobs, and this limits you being able to set goals, save and invest for the future. This will give you greater peace of mind when preparing for the future.
Qardus Ltd do not provide financial or investment advice. It is recommended that you seek your own independent advice from a qualified professional.
Non Fungible Tokens
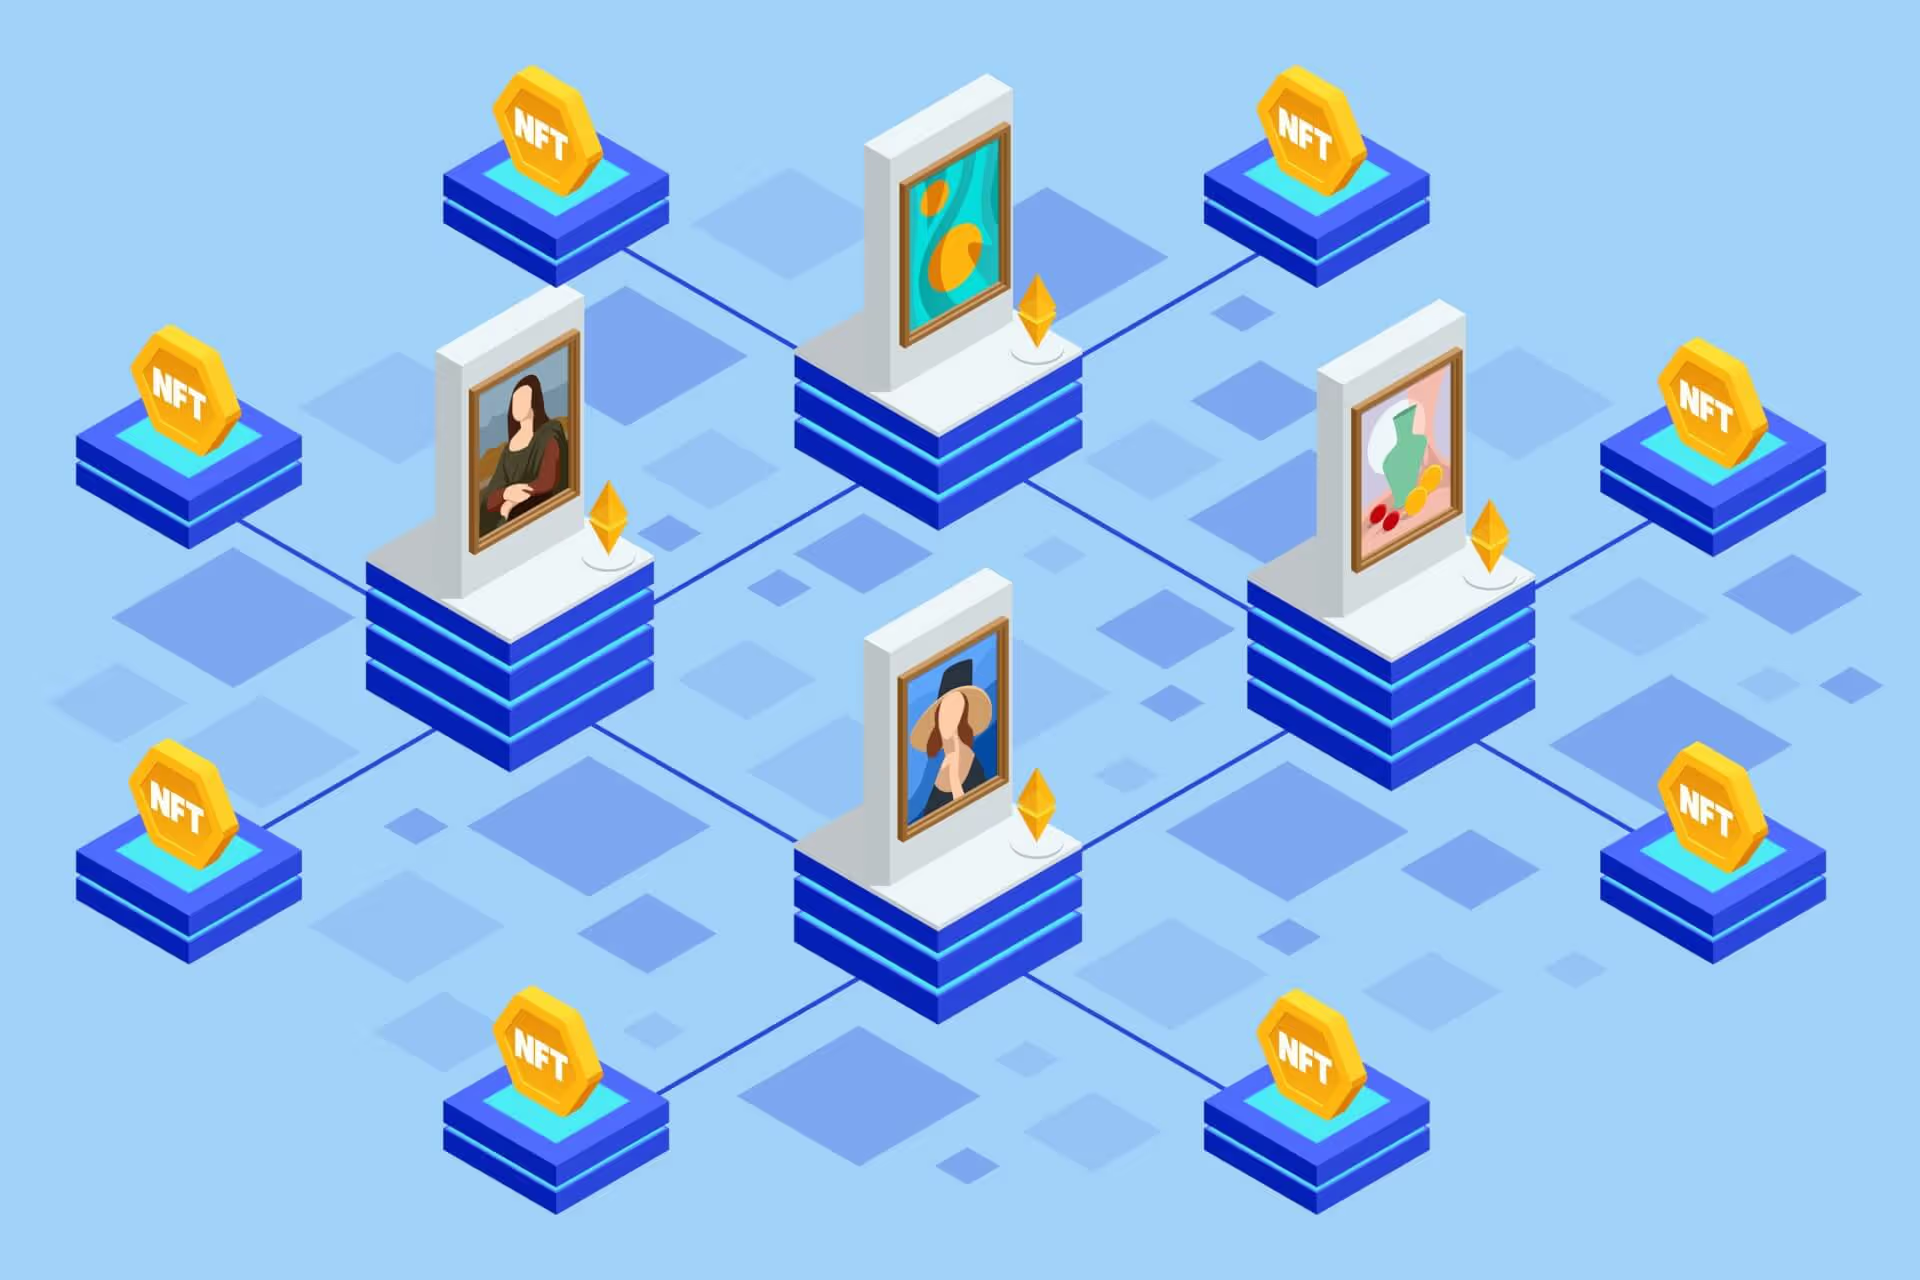
NFT stands for non-fungible token. Essentially, and explained very basically, NFTs are digital assets that can be traded online. Non-fungible tokens are not interchangeable with any other item and are therefore unique.
Currently, NFTs are taking the collectible and digital world by storm due to their popularity. NFTs enable creators to represent ownership of their very unique assets. The NFT itself is a token of ownership with clear and identifiable ownership trails. This means that there is an indisputable copyright status, and royalty protection.
The uniqueness of NFTs lies in the fact that they cannot be replicated. There can only be one owner at any time and the record of ownership cannot be fabricated as it is secured on the blockchain technology. NFTs have their own unique identifying code and this means they create their own digital scarcity.
As NFTs are unique digitally this means that no two NFTs will be the same and their uniqueness provides for a great financial investment opportunity.
Examples Of Nfts
Some examples of NFTs include the following:
- unique digital artwork
- trainers in a limited edition collection
- digital collectibles such as the Lebron James 'dunking against the Houston Rockets' moment
- internet domain names
- Internet GIFS such as the recent Taco Bell series of GIFS
- In-game items
- Ticketing for events
NFTs have exploded onto the mainstream because big brands and celebrities have started to realise how useful and lucrative they can be. High profile company Adidas recently launched a collaborative NFT partnership with Prada, and even McDonalds have added NFT to their marketing and advertising strategy.
These latest collaborations have made the news and brought NFTs firmly into the mainstream spotlight.
HOW DO NFTs WORK?
In its very simple form, NFTs work on the basis that they are not divisible, interchangeable, or assignable. The Ethereum blockchain technology enables the NFT to be fully traceable and trackable. Information about the NFT is stored securely on blockchain technology and this gives investors peace of mind and reassurance.Similar technology that is used for cryptocurrency investments is used for NFTs to guarantee the uniqueness of the NFT. The blockchain technology is the digital ledger that contains the proof of ownership. This means that it is impossible to create duplicates of frauds. This in turn means the price of NFTs can rise based on their features.
NFTs can include anything from digital files, photography, music, art, and videos. Recently, there have even been tweets from web content that have been made into NFTs.
Although NFTs have been around since 2014, 2021 was a bumper year for the NFT economy as NFT financial transactions and sales increased massively with investors building and diversifying their portfolios.
Difference Between Nft And Cryptocurrency
Although NFTs are built using similar technology to cryptocurrency, they are actually very different from cryptocurrency. NFTs are traded and generated using cryptocurrency.
However, unlike cryptocurrency, NFTs can't be exchanged because no two NFTs can ever be identical. What you are purchasing when you buy an NFT is a unique code that will manifest itself as a unique digital item.
For example, if you have multiple £10 notes in your wallet, these are interchangeable. You can use any one of them to make purchases. These notes are fungible - they are interchangeable. In contrast, consider the NFT sale of Jack Dorsey's first tweet that he sold for $2.9 million. This tweet is original and cannot be interchanged or replicated.
HOW TO MAKE MONEY WITH AN NFT
Many investors treat NFTs as they would a stocks and shares investment. They profit from buying and selling NFTs.
For collectors, NFTs are a great investment as they act as digital assets with proof of ownership that cannot be replicated. Each NFT has a digital signature that makes it impossible for it to be exchanged with like for like. Cryptocurrencies, in contrast, are considered to be fungible assets as they can be interchanged with each other.
For creators, they can create and sell their NFTs on various platforms and websites online that act in a similar way to Etsy or Amazon. These websites hold all the data relating to the NFT securely.
For investors, you can sell or trade NFTs. Of course, as with any investment you will need to know when the best time to sell is and factor in any kind of appreciation or depreciation of your NFT.
For many people, NFTs represent a fun but lucrative investment.
INVESTING IN NFTs - THE FUTURE
Although it is difficult to predict the future of NFTs, they are here to stay and experts predict that they will only increase in value and popularity. If wealthy investors continue to invest the NFT market will grow and move beyond gaming and art realms.
Investors looking for long-term investments that are likely to grow in popularity are drawn to NFTs as they have the potential to increase in value, quickly.For investors the main benefits are that NFTs provide the following:
- Proof of ownership
- Exclusive access
- Certifiable authenticity
- Marketplace efficiencies
- Safe blockchain technology
- Facilitate diversification
From a Sharia point of view, scholars understand that NFTs are still very much in their infancy. Any investor needs to ensure that no Sharia principles relating to assets and Islamic finance are breached. For example, investing in NFTs that operate within haram industries such as gambling, alcohol, or porn would be deemed impermissible under Sharia rules.
CAN MUSLIMS INVEST IN GOLD?
The Accounting and Auditing Organisation for Islamic Financial Institutions (AAOIFI) is widely recognised as a global leader of maintaining Islamic finance standards.
The rulings of the AAOIFI are accepted across Islamic markets. the AAOFI has led to many Islamic finance and Sharia-compliant gold products and services including investment options and accounts, EFTs, gold saving plans, and spot contracts.
IS INVESTING IN GOLD HARAM IN ISLAM?
According to the AAOIFI, there are certain standards that should be met when any Muslim considers investing in gold. These include the following:
- Gold should be traded on a hand to hand basis
- Gold can be jointly owned
- Gold ownership can be constructive or physical
- In each case, the gold should be completely allocated (with no ambiguity re ownership)
- Allocation can take place through settlement, certification, confirmation, or receipts.
Under Sharia rules, gold trading is haram if the following criteria are not met:
- the exchange of any metal including silver for silver and gold for gold must ensure that they are of equal weight and worth
- there must be an on the spot cash payment (no future options)
It is also very important to note that there can be no element of interest (riba) in the trade. When it comes to futures and options riba can sometimes occur in the deferment of the delivery or in the payment structure. To ensure riba is avoided, make sure the deal or transaction takes place and completes on the spot
WHEN IS GOLD TRADING NOT HALAL?
It is important to remember that whilst gold trading is deemed to be halal, speculative trading or gambling of any nature is not permissible in Islam.
For example, gold trading that involves futures and options contracts which usually involve elements of speculation could be deemed to be haram.
Under Sharia rules, a key component of compliance when it comes to investment and trading is that the asset should be physically backed. This is easy to achieve with gold as it is a real physical asset.
However, Muslims need to be aware of the Islamic finance rules relating to investment and trading, and the fact that gold is deemed to be a rabawi item.
This means that gold in itself cannot be traded for speculative purposes or future profit. It is halal to use gold as medium of exchange and a form of cash. Also, it is permissible to own gold as jewellery.
HOW CAN I INVEST IN GOLD IN A SHARIA COMPLIANT WAY?
To invest in a Sharia-compliant way you need to make sure that you comply with Islamic finance investment principles. You have to ensure that any investment portfolio is secured and managed in the correct way. Consult knowledgeable experts and ensure you understand Islamic finance rules.
Make sure of the following:
- Use a credible and acceptable form of payment. This could include bank transfer, bankers draft, cash, coin, or Sharia-compliant credit.
- The gold must be physical in the form of jewellery, gold coins, or bars.
- delivery and completion of the transaction and finance should occur on the spot
- Work with reputable agents who have verified transactions and parties and can validate the Sharia compliancy. In the UK and worldwide there are many banks and agents who are certified to work within the Islamic finance market.
- Whether you are a seller or a buyer, make sure you undertake your own due diligence and the terms of any investment are clear before you sign up to deal.
Managing and investing wealth in a Sharia-compliant way is the responsibility of all Muslims. It is imperative that Muslims ensure that as customers, sellers, investors, and buyers they are working towards compliance with Islamic rules and learning information about gold trading.
ARE GOLD CHAINS ALLOWED IN ISLAM?
Muslim men are not permitted to wear gold jewellery or adorn themselves in gold in any form. They are allowed to wear silver jewellery or jewellery made using stones.
Muslim women, however, are permitted to wear gold chains and jewellery.
When it comes to white gold, the ruling is the same. It is not permissible for men to wear white gold. This is due to the fact that white gold has high percentages of gold within it. This also applies to gold plated jewellery or any design or jewellery that contains gold as its main component. For Muslim men, it is best to stay away from gold jewellery.
HADITH RELATING TO GOLD?
One of the well-known hadiths relating to gold in Islam is the one relating to the Prophet Muhammad (PBUH) where he states that:
"Gold for gold, silver for silver.... like for like, equal for equal and hand to hand, then you may sell as you wish..'.
This hadith sets out some guidelines for transacting on gold and silver.
IS IT A GOOD IDEA TO INVEST IN GOLD?
There are many a website and platforms available that can provide you with information relating to investments and trading.
Gold trading is halal in Islam, and with gold prices increasing at high rates in the last few years alone, it is always a good idea to invest in gold. When it comes to the actual investment, there are many different options for Muslims looking to invest in a way that is Sharia-compliant and also yields a good return on investment.
Investing In Gold - Tips
There are various ways you can start to invest in gold today:
- look for reputable companies and agencies to use
- hold bullions or coins (or even shares)
- buy gold jewellery
- research and review EFTs and how they work
- avoid any form of riba
- focus on investing in physical gold
- diversify your investments
- consult Islamic scholars
Make sure you understand and make plans for the storage of any gold you buy. It is difficult and risky to store large amounts of gold (or any asset) at home so seek out storage companies who can help you.
HOW PROFITABLE IS GOLD TRADING AND IS GOLD TRADING HALAL?
Gold trading has always been profitable. Whether you trade in person or online, you need to understand that gold is expensive, and so trading and investment in it comes with its own costs. For example, spot price for gold can range between 5-10% so bear this in mind.
The easiest way to invest in gold is to actually buy it. Another great form of gold investment is EFTs. There are a wide range of Sharia-compliant EFTs on the market in the UK, USA and worldwide.
If you are looking at buying bullion and bars then this can be done via companies that can hold the gold asset for you.
IS LEVERAGE TRADING HALAL?
Leverage trading refers to borrowing funds in order the increase or amplify the potential return on any investment. As with any kind of trading, it is deemed to be halal as long as it conforms to Islamic rules about trading.
When you leverage trade you are borrowing cash to exchange with. This comes with greater risk than not borrowing. Is Islam, leverage trading would be deemed to be haram if interest is charged, or if the dealer of the leverage is using it for speculative activities.
As long as you use a halal broker who understand the Islamic finance rules, then leverage trading can be halal. In recent years the Islamic finance sector has created Sharia-compliant services that offer leverage trading or services similar to it.
Stay informed on finance