
NFT Investments
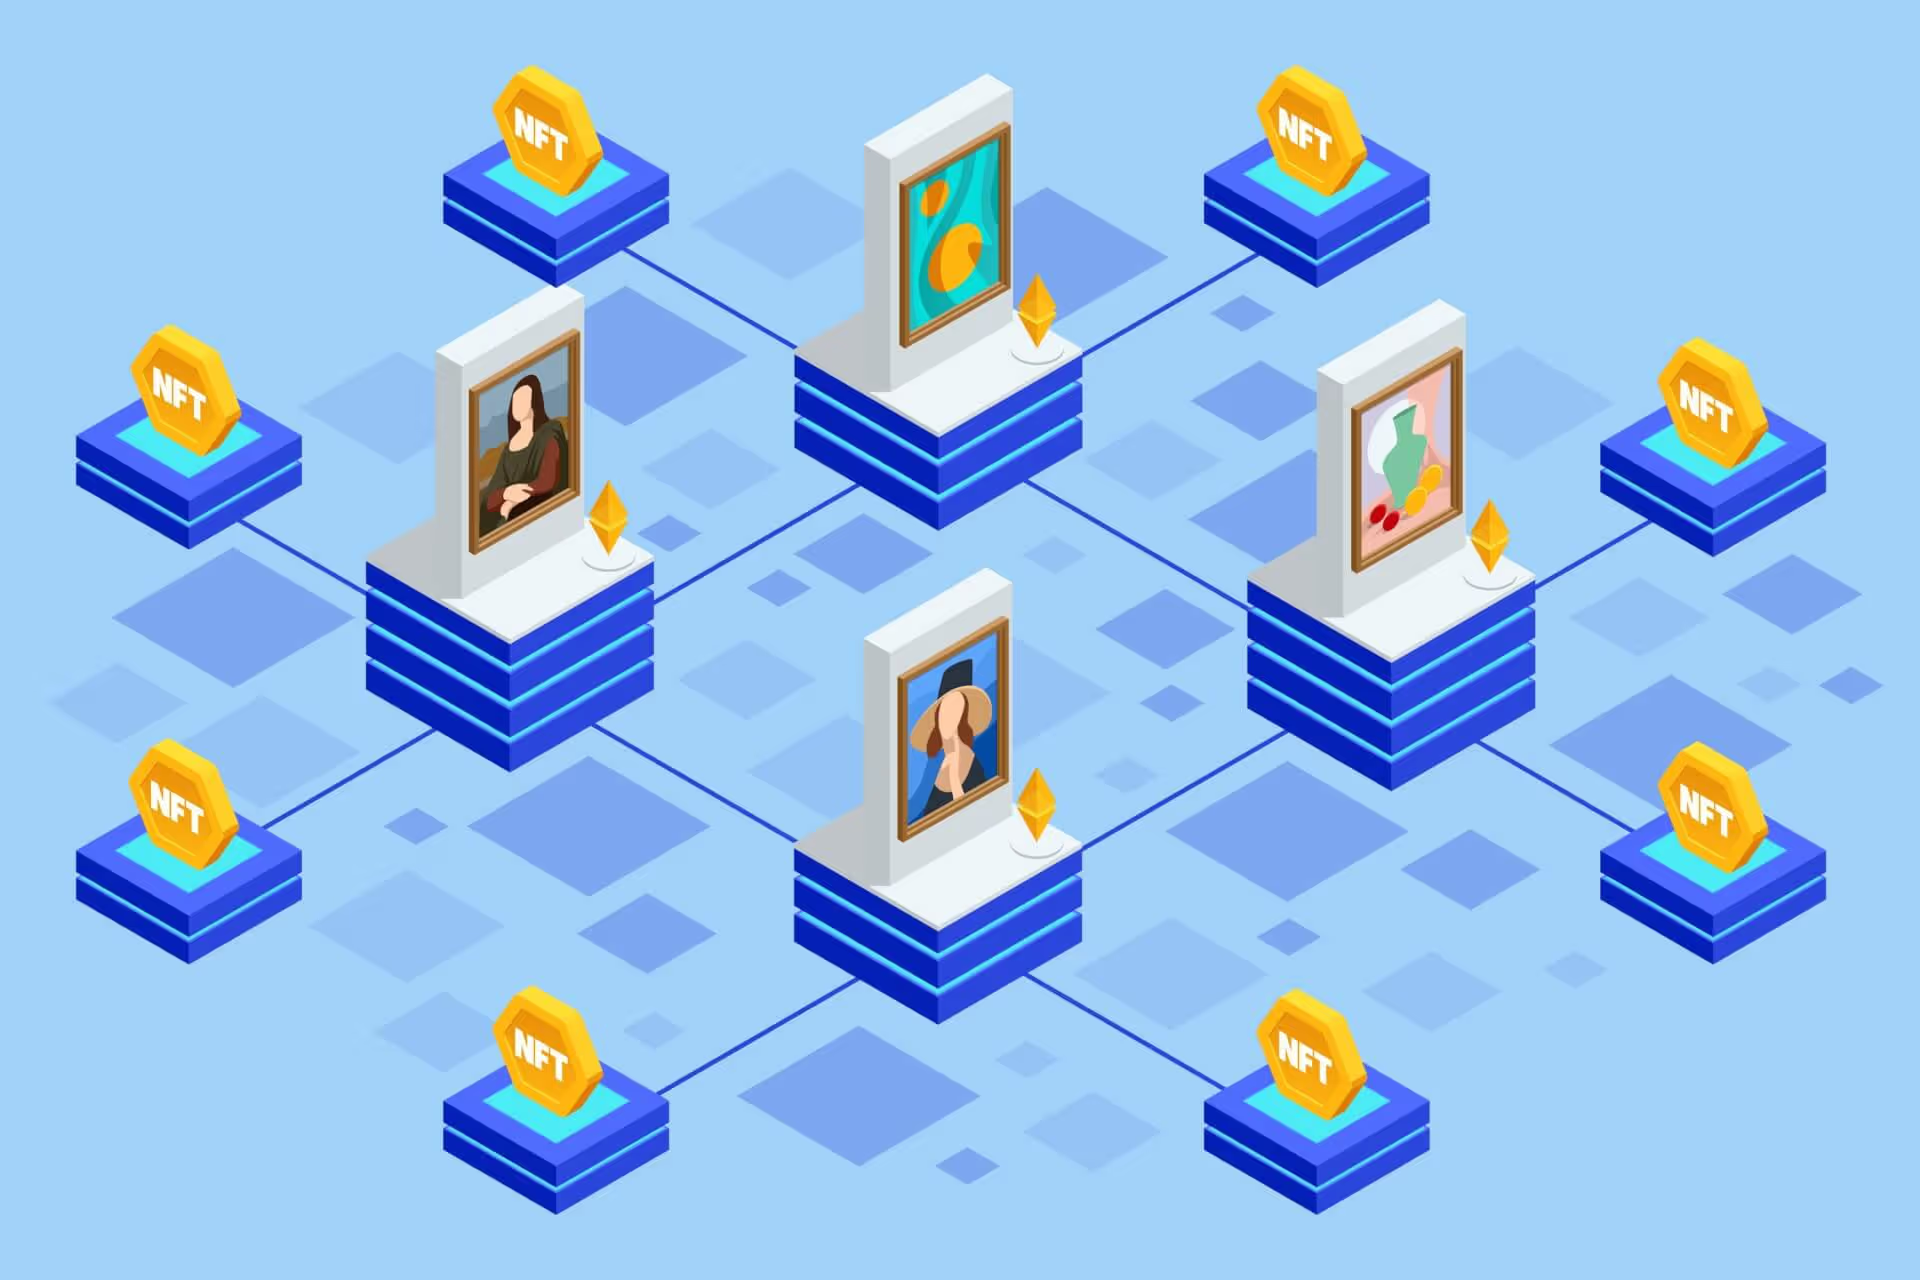

Non Fungible Tokens
NFT stands for non-fungible token. Essentially, and explained very basically, NFTs are digital assets that can be traded online. Non-fungible tokens are not interchangeable with any other item and are therefore unique.
Currently, NFTs are taking the collectible and digital world by storm due to their popularity. NFTs enable creators to represent ownership of their very unique assets. The NFT itself is a token of ownership with clear and identifiable ownership trails. This means that there is an indisputable copyright status, and royalty protection.
The uniqueness of NFTs lies in the fact that they cannot be replicated. There can only be one owner at any time and the record of ownership cannot be fabricated as it is secured on the blockchain technology. NFTs have their own unique identifying code and this means they create their own digital scarcity.
As NFTs are unique digitally this means that no two NFTs will be the same and their uniqueness provides for a great financial investment opportunity.
Examples Of Nfts
Some examples of NFTs include the following:
- unique digital artwork
- trainers in a limited edition collection
- digital collectibles such as the Lebron James 'dunking against the Houston Rockets' moment
- internet domain names
- Internet GIFS such as the recent Taco Bell series of GIFS
- In-game items
- Ticketing for events
NFTs have exploded onto the mainstream because big brands and celebrities have started to realise how useful and lucrative they can be. High profile company Adidas recently launched a collaborative NFT partnership with Prada, and even McDonalds have added NFT to their marketing and advertising strategy.
These latest collaborations have made the news and brought NFTs firmly into the mainstream spotlight.
HOW DO NFTs WORK?
In its very simple form, NFTs work on the basis that they are not divisible, interchangeable, or assignable. The Ethereum blockchain technology enables the NFT to be fully traceable and trackable. Information about the NFT is stored securely on blockchain technology and this gives investors peace of mind and reassurance.Similar technology that is used for cryptocurrency investments is used for NFTs to guarantee the uniqueness of the NFT. The blockchain technology is the digital ledger that contains the proof of ownership. This means that it is impossible to create duplicates of frauds. This in turn means the price of NFTs can rise based on their features.
NFTs can include anything from digital files, photography, music, art, and videos. Recently, there have even been tweets from web content that have been made into NFTs.
Although NFTs have been around since 2014, 2021 was a bumper year for the NFT economy as NFT financial transactions and sales increased massively with investors building and diversifying their portfolios.
Difference Between Nft And Cryptocurrency
Although NFTs are built using similar technology to cryptocurrency, they are actually very different from cryptocurrency. NFTs are traded and generated using cryptocurrency.
However, unlike cryptocurrency, NFTs can't be exchanged because no two NFTs can ever be identical. What you are purchasing when you buy an NFT is a unique code that will manifest itself as a unique digital item.
For example, if you have multiple £10 notes in your wallet, these are interchangeable. You can use any one of them to make purchases. These notes are fungible - they are interchangeable. In contrast, consider the NFT sale of Jack Dorsey's first tweet that he sold for $2.9 million. This tweet is original and cannot be interchanged or replicated.
HOW TO MAKE MONEY WITH AN NFT
Many investors treat NFTs as they would a stocks and shares investment. They profit from buying and selling NFTs.
For collectors, NFTs are a great investment as they act as digital assets with proof of ownership that cannot be replicated. Each NFT has a digital signature that makes it impossible for it to be exchanged with like for like. Cryptocurrencies, in contrast, are considered to be fungible assets as they can be interchanged with each other.
For creators, they can create and sell their NFTs on various platforms and websites online that act in a similar way to Etsy or Amazon. These websites hold all the data relating to the NFT securely.
For investors, you can sell or trade NFTs. Of course, as with any investment you will need to know when the best time to sell is and factor in any kind of appreciation or depreciation of your NFT.
For many people, NFTs represent a fun but lucrative investment.
INVESTING IN NFTs - THE FUTURE
Although it is difficult to predict the future of NFTs, they are here to stay and experts predict that they will only increase in value and popularity. If wealthy investors continue to invest the NFT market will grow and move beyond gaming and art realms.
Investors looking for long-term investments that are likely to grow in popularity are drawn to NFTs as they have the potential to increase in value, quickly.For investors the main benefits are that NFTs provide the following:
- Proof of ownership
- Exclusive access
- Certifiable authenticity
- Marketplace efficiencies
- Safe blockchain technology
- Facilitate diversification
From a Sharia point of view, scholars understand that NFTs are still very much in their infancy. Any investor needs to ensure that no Sharia principles relating to assets and Islamic finance are breached. For example, investing in NFTs that operate within haram industries such as gambling, alcohol, or porn would be deemed impermissible under Sharia rules.
Receive insights on ethical financing and Islamic finance directly to your inbox.
Explore more news
The purpose of Debt Consolidation is to reduce your debt and reshuffle it to make it more affordable to pay off.
Debt Consolidation works by combining multiple debts into one manageable pot. For example, if you have numerous debts that have a combined total of £10,000, you can get a single £10,000 loan to pay off those debts. You then would repay the £10,000 loan in one single monthly repayment.
Debt Consolidation can also reduce the interest you need to pay by having all your debt in one pot, at a lower interest rate.
Overdraft loans can take different forms, such as cash advances, business debt, and credit card debt. Keeping track of various debts and the interest required to be paid on them can be exhausting and time-consuming.
You may have various debts from different providers, but these debts are first paid in full before monthly repayments are made to a single provider. This way you are only accountable to one provider, keeping things simpler and straightforward.
For example, Sarah has a credit card with Santander, an overdraft with Barclays, and an asset finance loan she’s taken against a product. Consolidating these debts into a single loan allows Sarah to gradually chip away at her debts to one single provider.
Another example would be Ahmed, who takes out two business loans with the same provider. He now wants a third to invest further into his business. Just like Sarah, Ahmed can consolidate the loans he has already taken into one, straightforward loan from a single provider.
WHAT ELSE CAN DEBT CONSOLIDATION BE USED FOR?
Examples of different types of debt a consolidated loan can be used to combine:
- Credit card debt (consolidated loans help reduce the impact of the high APR - annual percentage rate - charges most credit cards have).
- Personal loan debt (these are often used to fund a car purchase, a holiday, or home improvements).
- Overdraft (most banks charge high-interest rates on overdrafts which can lead to substantial debts that can be financially crippling).
- A Store Card (like credit cards, store cards often have high APRs and fees, despite initially offering front-end discounts).
- Payday Loans (loans which can be paid directly into your bank account but have high-interest rates attached that can make repayment difficult).
- Bailiff debt (such as unpaid Council Tax bills, parking fines, court fines and county court, high court or family court judgments).
How Debt Consolidation Works
First, you’ll need to establish the total sum of your existing debts.
You can then take out a loan which will cover the total cost of the outstanding debt. When you’re looking for a new provider for a debt-consolidating loan, you will want to find a loan that works with your budget.
The idea is to create straightforwardness, simplicity, and manageability by consolidating your debts. So when choosing a new loan provider you’ll want to pick a loan repayment plan which is manageable within a reasonable time frame you know you can pay the loan back in.
Like any other loan, a debt consolidation loan is available in two forms:
AN UNSECURED LOAN
This is a personal loan that does not require an asset, such as your home, to act as security for the loan.
A SECURED LOAN
This is a loan in which you attach an asset, like your home or a car, as security. In the instance where you are unable to repay the agreed-upon loan, the loan provider can repossess the asset put forward by you as a security, where they can then sell it and recoup the loan by another means.
The Pros And Cons Of Debt Consolidation
BOOSTING YOUR CREDIT SCORE
Keeping to a single monthly repayment consistently will improve your credit score, giving you greater financial flexibility into the future. Alternatively, your credit score may be at risk if you cannot meet the monthly repayments.
LOWER OVERALL INTEREST RATES
Debt consolidation loans often have lower APRs than alternatives like payday loans, or credit cards.
EASIER DEBT TRACKING
Managing one repayment a month is much easier than several at a time.
YOUR ASSETS MAY BE AT RISK
If you choose a secured loan any asset you use as security for that loan will be at risk. This could be your home, car, or any asset the loan provider can reasonably be expected to sell should you be unable to meet the monthly loan repayments.
Ways To Consolidate Debt
O% INTEREST, BALANCE-TRANSFER CREDIT CARD
Balance-transfer credit cards are designed to let you move existing debt from one credit card - or several - to another card from a different provider. The purpose of this is to pay less interest on the transferred money. By doing this you will be able to clear your debt faster, because all of your repayments will be going towards paying off your debt, instead of being used to cover the interest.
When you receive a balance-transfer credit card you pay off the balance on your existing credit card using the new credit card. You then make repayments on your new balance transfer card to pay off the debt.
By using a 0% balance transfer card, you won’t be charged interest on the transferred balance for the duration of the interest-free period.
A DEBT CONSOLIDATION LOAN
A debt consolidation loan can help you gain greater control over your finances. Debt consolidation loans often offer terms between one and five years. In general, longer loan terms require you to borrow a more significant amount of money, so they may not be available if your consolidation loan is less than £10,000.
FEES AND CHARGES FOR DEBT CONSOLIDATION LOANS
It’s important to be aware of some of the high fees some companies charge for arranging a loan. You should read the small print carefully for any extra fees or charges before you sign anything. Check to see if there are any costs associated with paying off the existing loans early. This could cancel out any savings you make. Avoid paying a fee for a company to arrange the loan on your behalf, that is, unless you’re receiving advice and you’re sure it's worth the cost.
IF YOU CHOOSE A DEBT CONSOLIDATION LOAN
Get advice before you make a final decision. If you choose to go ahead with a consolidation loan, it may be worth talking with an independent financial adviser who might be able to find the most suitable product for your needs. Avoid just looking at the annual percentage rate (APR), or the annual percentage rate of charge (APRC) for secured loans. The APR is the interest you’ll be charged, and the APRC will include the extra costs such as an arrangement fee.
Qardus does not provide financial advice.

As more and more people attempt to get their foot onto the property ladder, this article will examine in detail the alternatives to conventional mortgages. In recent years there has been significant growth in alternatives to traditional mortgages, and what this means in principle is more choice for those looking to purchase assets or property in a Sharia compliant way.
There are many different reasons why people look for alternatives to mortgages:
- Flexibility: people want more flexibility when it comes to financing property or asset purchases.
- Accessibility: for some investors, alternatives to interest-based mortgage products are problematic as they contravene Islamic finance rules and ethical investment principles.
- Cost: alternative mortgage products can be cheaper overall than the standard mortgage products available in the UK, especially for those with poor credit scores.
- Less risky: there is sometimes less risk associated with alternative mortgages.
ALTERNATIVE MORTGAGES - WHY?
A conventional mortgage arrangement exists as a loan between a lender (bank) and an individual or company. The lender lends you the money to buy the property and in return, the borrower repays the money they have borrowed plus interest.
The mortgage loan itself is secured against the property and against the value of the property.
For many potential homeowners, a conventional mortgage is not a viable option, especially those looking for Islamic finance or ethical mortgages.
One of the main reasons traditional mortgages are shunned is that they are interest-centred and therefore not Sharia compliant. This has led to Muslims and ethical investors looking for alternative financial products to source funding when buying a property.
Interest is strictly prohibited under Islamic finance rules, so Muslims have had to look outside the traditional mortgage market in order to secure funding for their real estate and asset purchases.
However, it is not only Muslims who are looking at the market for alternatives to traditional mortgage products and services. As the ethical finance market continues to grow, many ethical investors and purchasers are also looking to secure funding that comes without hefty interest payments and charges.
Islamic banks and products under the Islamic finance banner are often considered to be a safer option than the finance options available on the mainstream finance market. The reason for this is that they are seen as less risky and less speculative.
Let's have a look at the alternatives out there and whether or not they are deemed to be halal or haram under Sharia rules.
Buy To Let Loans
Buy-to-let mortgage loans are designed for those people or businesses who want to purchase real estate properties with the purpose of renting the property out. Once the property is let, the homeowner then generates revenue through the rent payments they receive from the tenant.
Normally, these types of mortgages are based on higher interest rates than conventional mortgages and for this reason alone they are not Sharia compliant and are deemed to be haram.
There are some Islamic banks within the UK that offer a buy-to-let mortgage product, and if you want to review what is on offer you need to make sure that the product is 100% Sharia compliant.
Certainly, conventional buy-to-let mortgages that include interest in the repayment structure are not permissible for Muslims.
Home Purchase Plans
Home purchase plans are structured to avoid the charging and paying of interest. Normally a home purchase plan will involve the bank and the homeowner taking part in a shared investment strategy.
The bank, or financial institution, will purchase the property outright on behalf of the homeowner. The bank and the homeowner will agree the payments that the homeowner will make to the bank in lieu of repayment.
The homeowner will then make the repayments to the bank until they have paid off the pre-agreed price of the property. Once all the payments have been made the homeowner will own the property outright.
Home purchase plans give customers the opportunity to get on the property ladder in a halal and Sharia compliant way.
This type of co-ownership arrangement means the bank and the borrower share the risk and no interest is payable.
Shared Ownership Schemes
A shared ownership mortgage enables the purchaser to buy a share of the property. The purchaser then pays rent on the remaining share which is often owned by a non-profit organisation such as a registered social housing provider.
Shared ownership schemes were developed to enable people to get on the property ladder in an affordable way.
When structured correctly, shared ownership mortgages can be halal. If the share (of ownership) being purchased is clearly defined, and the rent on the remaining share is based on payments which are fair then this could be considered a halal alternative to an interest-based mortgage.
Make sure that the rental payments do not attract any interest, and that the terms and conditions of the ownership scheme are clear and concise. In the United Kingdom, shared ownership schemes are regulated and can often be an effective way to get on the property ladder.
If you are interested in a shared ownership scheme, look to see if they are being offered in your local area, and then look to see if any Islamic banks are offering shared ownership services.
Guarantor Mortgages
Guarantor mortgages are for those people who are unable to purchase a property, or secure funding to make the purchase, on their own.
A guarantor is involved who guarantees that they will repay the mortgage loan amount if the borrower does not make the payments.
Usually, the guarantor is a family member or close friend.
Whilst Islamic finance does permit the concept of a guarantor, in order for the service to be halal it needs to follow Sharia rules relating to such transactions. For example, a guarantor can be involved in a joint purchase transaction. In this type of financial transaction, the guarantor owns a share of the property and the risks are shared.
This is a musharakah arrangement - that is a profit-sharing arrangement or partnership.
If the guarantor mortgage is simply one where the guarantor guarantees the loan repayments with zero ownership rights then this is not permissible under Sharia rules.
Crowdfunding
Crowdfunding is a relatively new alternative to conventional mortgages. In its very basic form, crowdfunding operates by way of a collection of funds from a crowd of people (investors).
Whilst historically, investment markets have tended to be reliant on interest. However, Islamic crowdfunding is an activity that is deemed to be halal. Funds collected from a community have never been prohibited. In fact, crowdfunding in its very essence can have a positive social impact and this is a key principle of Islamic finance - social responsibility and ethical finance.
Anyone considering crowdfunding should ensure that the crowdfunding arrangement is set up to be fully Sharia compliant.
Self-Build Mortgages
Self-build mortgages are for those people who want to build their own homes. What this means in principle is that the loan is released to the borrower in stages that coincide with the stages of the build taking place. The final loan amount if based on the value of the property once it has been fully completed.
This type of alternative to the conventional mortgage is not halal as it still incurs the same type of interest payment as a standard up-front mortgage does.
Conclusions
Muslims have been wanting Sharia compliant alternatives to standard mortgages for many years. To address this, banks in England and other western economies have developed Sharia compliant alternatives that enable Muslim and ethical investors to buy a house or a business property/asset.
Halal alternatives to interest-based mortgages have several unique features. They are less risky, less speculative, and more socially responsible.

Introduction
A pension fund is a pool of money that is managed by professional fund managers. The aim of the fund is to save money and invest money in preparation for retirement. A Sharia pension fund is a saving scheme for retirement that aligns with the rules of Islam. Sharia pension funds do not attach themselves to any form of interest or any haram industries.
Sharia pension funds are ethical investments, with funds invested in industries that offer social benefits such as healthcare, agriculture, and education.
With the rise of Islamic finance on a global level and the increased demand for Sharia-compliant financial services, the growth of Sharia pension funds has expanded significantly.
Sharia pension funds will typically have a screening process ensuring they comply with Islamic finance rules. It is important for these types of pension funds to have ongoing compliance monitoring, which means that a qualified Sharia scholar or expert reviews compliance regularly.
In 2024 Sharia pension funds saw significant growth. The Nest Sharia Fund increased its assets by a third to over £180 million.
Historically, Muslims have found it difficult to fund Sharia-compliant funds. The Office for National Statistics found in 2021 that 33% of Muslim employees did not have a workplace pension due to concerns about Sharia-compliance.
These statistics make it clear that there is a huge market for pension funds that comply with Islamic finance principles. Recently, the Financial Times has reported that Sharia pension funds are seeing a huge swell 'amid returns boost'.
WHAT MAKES A PENSION FUND SHARIA-COMPLIANT?
The key features of a Sharia-compliant pension fund are:
- Strictly no interest: the pension fund should have no involvement with interest in any way. This means that any interest-yielding activities, industries or products are not permissible.
- Ethical investing: the pension fund should be mindful of the industries the investments are involved in. Industries and sectors considered haram such as gambling and alcohol should be avoided.
- Compliance: compliance and ongoing monitoring are essential for a Sharia complaint pension fund.
- Sharia screening: financial and ethical screening must take place to ensure that organisations invested in have low levels of overall debt.
- Models of operation: profit-sharing and risk-sharing are the encouraged models of partnership working.
Some examples of Sharia-compliant funds include the following:
- sukuk/Islamic bonds
- investing in property without interest-based loans
- investing in ethical and sustainable industries such as healthcare
Comparing Top Sharia Pension Plans
If you are looking for Sharia-compliant pension funds to ensure you can save for retirement without breaching Islamic rules, then Penfold and Nest pension funds are a good place to start.
Nest Sharia Pension Fund
The Nest Sharia Fund invests in what are known as Islamic bonds (sukuks) that are fully Sharia-compliant. Nest ensures that Islamic scholars screen the investment products and services to ensure they adhere to Islamic rules.
In addition, Nest's Sharia Fund avoids haram industries and interest-bearing investments.
Nest's fee structure consists of a contribution charge (around 1.8%) and an annual management charge in the region of 0.3% based on the value of the fund.
With ethical investments at the core of its activities, the Nest Sharia Fund delivers growth whilst generating income. More recently, Nest has worked on diversifying its investment portfolio to include a 30% allocation to the sukuks it invests it.
Penfold Sharia Pension Fund
The Penfold Sharia Fund invests in a diverse portfolio of companies and funds that all operate in accordance with Sharia principles.
The Penfold fee structure charges an annual fee for savings up to £100k of 0.88%, and this fee drops to 0.53% on amounts over £100k. This transparent and easy to follow fee structure makes this pension fund attractive to investors.
Both these Sharia pension funds use rigorous screening processes that aim to ensure that all investments comply with Islamic finance rules.
If any company they invest in has a proportion of what is considered to be non-compliant income (ie income from interest), then they use purification processes such as donating money to charity.
Investment Risks And Rewards
Sharia pension funds are the same as all investment vehicles on the market. They come with their own unique set of risks and rewards. For Sharia pension funds, the risk management and mitigation strategies should be aligned with Islamic rules.
Sharia pension funds tend to avoid fixed income securities and conventional bonds as these vehicles rely on interest. Instead, Sharia pension funds prefer to invest in Islamic bonds.
Risk
The risk profile for Sharia pension funds can sometimes have a higher risk exposure due to the fact that they stay away from conventional interest-bearing bonds.
Return
In the long term, Sharia-compliant funds deliver comparable and competitive returns to conventional bonds.
Ethical Investments Vs Conventional Funds
It is important to note that Sharia pension funds maintain a balance between competitive financial returns and ethical investment strategies. This makes Sharia funds an attractive option for investors.
If you are looking for investments that focus on societal benefit whilst generating an income (or savings pot) then Sharia pension funds are a great alternative to conventional bonds.
Ethical sectors have seen a massive resurgence in recent years, with strong growth potential. Industries such as renewable energy and technology are prime for investment.
Investors are increasingly considering environmental, social and governance (ESG) factors when examining pension funds.
- Over 89% of investors consider ESG when investing.
- In the UK over 57% of investors now hold ESG investments
- Young Gen Z investors are increasingly interested in ethical investments
- Islamic funds continue to deliver results with nominal growth rates of 84% and 13% of annualised growth rates (Morningstar.CA)
How To Choose And Switch To A Sharia Pension Fund
In order for you to choose a Sharia pension fund you need to ensure you understand what a Sharia pension fund is and how it operates.
If you have a pension fund that you want to switch to a Sharia fund then you need to:
- Review your current pension fund.
- Find out if your pension fund provider is able to offer a Sharia-compliant fund.
- If not, ask if you can switch your pension fund.
- Check your pension fund information to see if there are any penalties or fees for switching to a Sharia-compliant provider.
- Research what Sharia pension fund providers are available and make sure they are fully Sharia compliant.
- Choose your new pension fund provider and open an account.
- Ask your current pension provider to transfer your fund to the new Sharia-compliant provider.
If you want to transfer a workplace pension then speak to your HR team or your employer to find out if they accept transfers of the fund.
Switching to a Sharia pension fund should be straightforward.
Future Of Sharia Pension Funds
Sharia pension funds are becoming a popular investment vehicle and retirement savings plan for Muslims and non-Muslims. The ethical investment market continues to grow as investors across the world seek out sustainable and ethical investments.
Underpinned by social responsibility, the investments within Sharia pension funds appeal to a global audience of investors.
Sharia funds have become known in financial circles as promoting financial inclusion. They cater to investors who have not been able to fund ethical investments or investments that align with Islamic rules.
If you want to prepare for retirement in a Sharia-compliant way then Sharia pension funds provide the perfect vehicle for you. Providers like Penfold and Nest provide Sharia-compliant pension funds with competitive fees.
Stay informed on finance
