
What is a sukuk

A sukuk is a form of financial certificate that is issued in compliance with Islamic finance principles and Sharia law. Sukuk is an Arabic word meaning 'deed, cheque, or legal instrument'.
The main purpose of a sukuk is to create returns for investors that are similar to the returns available on traditional fixed income bonds.
As the Islamic finance market has grown over the last few decades, so has the interest in and demand for sukuk bonds. Essentially, sukuk bonds are similar to traditional bonds in that they have parties who are involved in seeking a return on investment, and sukuk bonds are subject to the same credit rating as conventional bonds.
Sukuks are commonly used by corporations and even governments to finance their business operations.
Islamic Finance Principles And Sukuk
Sharia law does not permit investors to partake in investment activities that involve riba. The payment or receipt of riba (interest) is strictly forbidden in Islam.
Most conventional Western market bonds are based on an interest paying structure, and this is not permissible for investors who do not want to receive or pay interest on their financial investments.
Sukuks were first issued over a decade ago in Malaysia who were forward-thinking when it came to creating and supporting financial investment products that Muslims could be involved in. Bahrain was quick to follow Malaysia in issuing sukuks, and these days sukuks can be found in economies across the globe.
Sukuks take up a respectable share in the fixed income market globally. Sukuks have emerged as a great Sharia compliant alternative to traditional interest based bonds.
Sukuks offer Muslim investors the opportunity to invest in bonds and subscribe to certificates that represent the right to actually receive a share of profits that are generated by an asset base. The profits are generated by the asset base being traded on the market.
What do we mean when we refer to fixed income bonds? Sukuks are fixed income bonds. This means that they are fixed income investments and they can provide what is considered to be a more steady stream of income.
Islamic Bonds
Sukuks are considered to be Islamic bonds. They involve asset ownership which is direct, rather than indirect interest based bonds that Western markets tend to offer.
Any income, return, or profits generated from a sukuk cannot be derived from any speculative activity. This would render the return haram under Sharia laws.
So, how do sukuks work? What normally happens is that the issuer of the sukuk certificate will sell an investor a certificate. The proceeds of the sale are then used towards the purchase of an actual asset. The investor then has a partial interest in the asset based on their respective investment.
Another element of sukuk that is important to note is that the issuer of the certificate must promise that they will buy back the sukuk at a future date.
When it comes to sukuks, compliance with Sharia law means that any profits that are derived from the investment must be totally free of speculative activity and interest.
Sukuk Versus Traditional Bonds
As Islamic finance rules do not permit interest, this means that the traditional Western debt and loan instruments are not accessible to Muslim investors who want to comply with Sharia rules.
Sukuks have therefore become a great alternative for investors (Muslim and non-Muslims) to use sukuks as a viable alternative method of raising funds.
Sukuks are considered to be an interest in an asset, and not a debt obligation or debt instrument.
Conventional bonds and sukuks do have some similarities:
- Both traditional bonds and sukuks offer investors a stream of income payments. The payments on traditional bonds include interest payments, and the payments from sukuks are based on profits from the assets.
- Both bonds and sukuks are sold initially by issuers of the certificates.
- Sukuks and bonds are viewed as less risky than equity based investments
When it comes to ownership, sukuks allow for partial ownership of the asset, whilst conventional bonds are more of a debt obligation. Sukuks are not debt obligations.
It is also important to note that often, conventional bonds finance businesses or industries that are deemed to be haram under Sharia law principles. These haram industries include the gambling industry, alcohol industry, and porn industry. Sukuk bonds cannot be linked to any form of haram activity or industry.
HOW ARE SUKUK CERTIFICATES ISSUED AND HOW DO THEY WORK?
Sukuks are usually found in the form of certificates, also known as trust certificates. In the United Kingdom, sukuk certificates are regulated by the Financial Services Authority. In other countries and economic landscapes across the world where sukuk certificates are issued, there is similar regulation of them.
There is a very specific process for issuing any form of financial certificate including sukuk certificates/ bonds.
The steps below outline the most common steps that are involved in issuing a sukuk certificate:
- Normally a company that requires some form of capital will establish a special purpose vehicle that is known as an SPV for short.
- The company is known as the originator.
- The special purpose vehicle aims to protect the underlying asset from potential creditors in the event that the originator gets into financial difficulties.
- The special purpose vehicle issues the sukuk certificates.
- These sukuk certificates are then sold on to investors for a price.
- The originator uses the funds raised from the sale of the sukuks to purchase the asset they want.
- The special purchase vehicle will then purchase the asset from the originator.
- The special purpose vehicle will then establish a form of lease to lease back the asset to the originator.
- The originator will make the necessary lease payments to the special purpose vehicle.
- The special purpose vehicle will then distribute the lease payments to the investors.
- Once the lease is terminated, the originator will buy back the asset from the special purpose vehicle at nominal value.
- The proceeds of the sale are then distributed by the special purpose vehicle to the holders of the certificate.
Different Types Of Sukuk
As mentioned above, most sukuk certificates have been presented in the various global markets as trust certificates. It is very common for English common law to govern the law relating to sukuk trust certificates in different countries.
However, the management of sukuks varies from country to country so it is always advisable to do your research about the jurisdiction that regulates your sukuk. Information and transparency are key when it comes to any form of investment, especially sukuks. Where possible, always carry out an analysis of the sukuk product or service before you proceed.
The main types of sukuk are as follows:
- Trust certificates - in this form of structure the originator of the sukuk will create the special purpose vehicle and issue trust certificates to the investors. The proceeds are then used to build a portfolio of assets which will eventually yield a return.
- Civil law structures - these types of structures have emerged to enable sukuk transactions to be undertaken in accordance with the local laws of the country where the originator is based. One example of a country that used civil law structures when it comes to sukuks is Turkey. Turkey have passed their own legislation relating to sukuks which has to be complied with.
Sukuk For Investors
As Muslim investors have historically not had the opportunity to invest in bonds without an interest element, sukuk bonds have been welcomed across many global economies.
Sukuks are a great way of enabling investors to link returns with the cash flow of financing assets without the riba of traditional form of debt financing.
However, it is important to point out that sukuks as a form of financing should only be used for identifiable assets. Identifiable assets are those assets whose commercial value can be ascertained at any given point of time. Identifiable assets include things like real estate, equipment, cash, and stock.
In this way, the holder of the sukuk bond /certificate does not own a debt, but as the owner of the sukuk certificate, they own a share of the asset that is purchased using the sukuk funds.
Even though the special purpose vehicles that issue the sukuk certificates are usually brand new, this does not mean that investors will bear exposure to the credit risk of that special purpose vehicle.
Advantages Of Sukuk
Here are some of the main advantages of investing in sukuks:
- For those looking for investment from Islamic economies and markets there is a great marketing benefit to sukuks who will appeal to investors looking for Sharia compliant ways of investing their money
- Sukuks are known to yield similar profit on par with conventional bonds
- More bank and financial institutions are offering sukuk products (always check the website of any organisation offering Sharia compliant products to ensure that you have all the information you need)
- The investor base of Sharia compliant investors is vast and continues to grow
- In addition to the Islamic finance investment market, there is also potential to tap into the ethical investment market which has developed over the last few decades and is always in the news
- Issuers of sukuk certificates are entitled to the same tax arrangements as the equivalent traditional financing arrangements
- Assets that are acquired by the sukuk bonds are jointly owned
- Instead of receiving interest, the holder of the sukuk certificate receives actual profits
- Sukuks offer banks the opportunity and tools to invest their excess liquid assets
- Sukuks can operate for contractual terms that are agreed upon between the parties
- Sukuks continue to grow with success attracting all kinds of high-quality investors including Muslim and non- Muslim investors
- Sukuks have been used across various locations and industries including transport, water, power, education, infrastructure and industrial
Receive insights on ethical financing and Islamic finance directly to your inbox.
Explore more news
Non Fungible Tokens
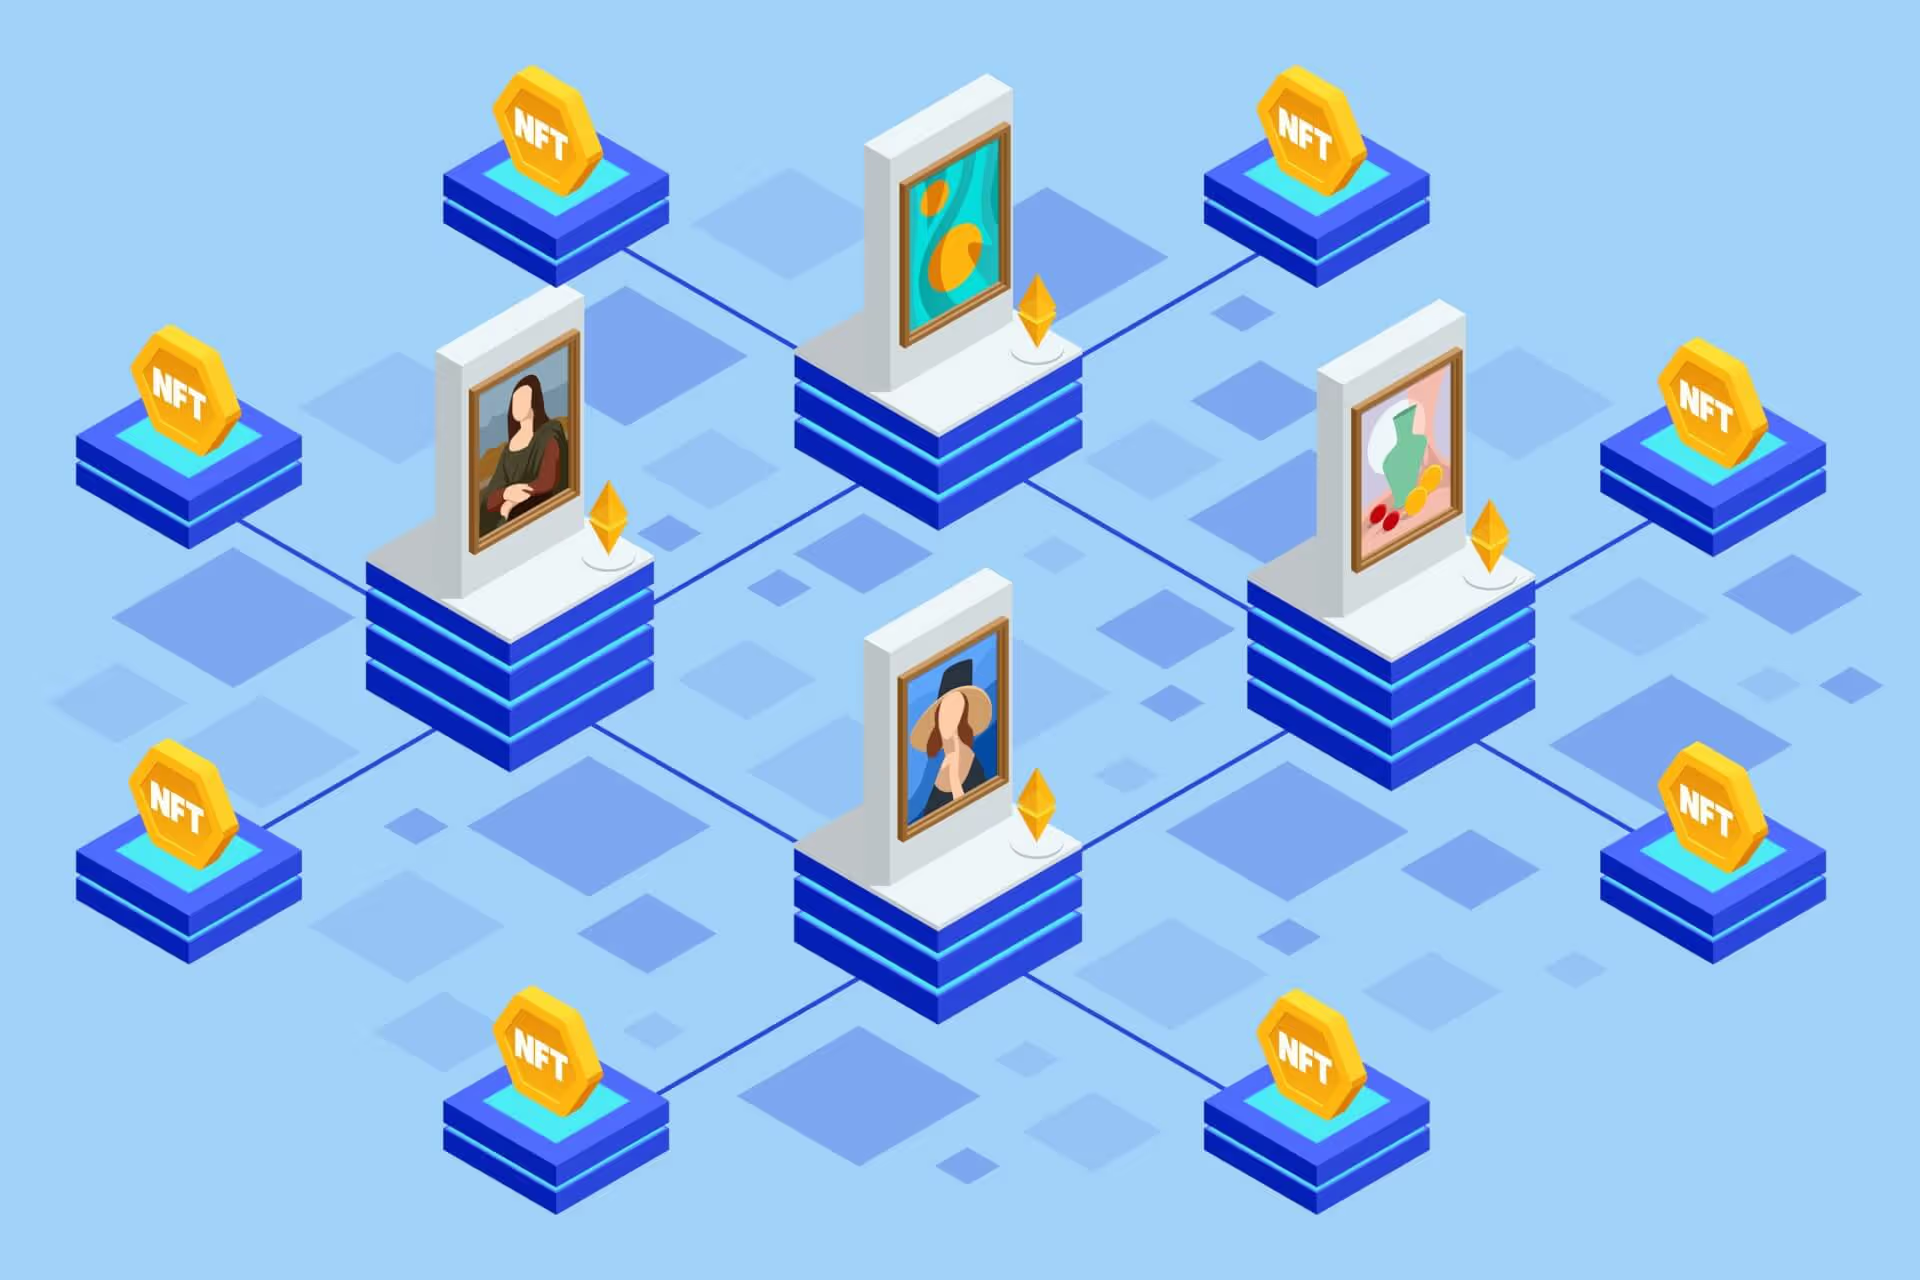
NFT stands for non-fungible token. Essentially, and explained very basically, NFTs are digital assets that can be traded online. Non-fungible tokens are not interchangeable with any other item and are therefore unique.
Currently, NFTs are taking the collectible and digital world by storm due to their popularity. NFTs enable creators to represent ownership of their very unique assets. The NFT itself is a token of ownership with clear and identifiable ownership trails. This means that there is an indisputable copyright status, and royalty protection.
The uniqueness of NFTs lies in the fact that they cannot be replicated. There can only be one owner at any time and the record of ownership cannot be fabricated as it is secured on the blockchain technology. NFTs have their own unique identifying code and this means they create their own digital scarcity.
As NFTs are unique digitally this means that no two NFTs will be the same and their uniqueness provides for a great financial investment opportunity.
Examples Of Nfts
Some examples of NFTs include the following:
- unique digital artwork
- trainers in a limited edition collection
- digital collectibles such as the Lebron James 'dunking against the Houston Rockets' moment
- internet domain names
- Internet GIFS such as the recent Taco Bell series of GIFS
- In-game items
- Ticketing for events
NFTs have exploded onto the mainstream because big brands and celebrities have started to realise how useful and lucrative they can be. High profile company Adidas recently launched a collaborative NFT partnership with Prada, and even McDonalds have added NFT to their marketing and advertising strategy.
These latest collaborations have made the news and brought NFTs firmly into the mainstream spotlight.
HOW DO NFTs WORK?
In its very simple form, NFTs work on the basis that they are not divisible, interchangeable, or assignable. The Ethereum blockchain technology enables the NFT to be fully traceable and trackable. Information about the NFT is stored securely on blockchain technology and this gives investors peace of mind and reassurance.Similar technology that is used for cryptocurrency investments is used for NFTs to guarantee the uniqueness of the NFT. The blockchain technology is the digital ledger that contains the proof of ownership. This means that it is impossible to create duplicates of frauds. This in turn means the price of NFTs can rise based on their features.
NFTs can include anything from digital files, photography, music, art, and videos. Recently, there have even been tweets from web content that have been made into NFTs.
Although NFTs have been around since 2014, 2021 was a bumper year for the NFT economy as NFT financial transactions and sales increased massively with investors building and diversifying their portfolios.
Difference Between Nft And Cryptocurrency
Although NFTs are built using similar technology to cryptocurrency, they are actually very different from cryptocurrency. NFTs are traded and generated using cryptocurrency.
However, unlike cryptocurrency, NFTs can't be exchanged because no two NFTs can ever be identical. What you are purchasing when you buy an NFT is a unique code that will manifest itself as a unique digital item.
For example, if you have multiple £10 notes in your wallet, these are interchangeable. You can use any one of them to make purchases. These notes are fungible - they are interchangeable. In contrast, consider the NFT sale of Jack Dorsey's first tweet that he sold for $2.9 million. This tweet is original and cannot be interchanged or replicated.
HOW TO MAKE MONEY WITH AN NFT
Many investors treat NFTs as they would a stocks and shares investment. They profit from buying and selling NFTs.
For collectors, NFTs are a great investment as they act as digital assets with proof of ownership that cannot be replicated. Each NFT has a digital signature that makes it impossible for it to be exchanged with like for like. Cryptocurrencies, in contrast, are considered to be fungible assets as they can be interchanged with each other.
For creators, they can create and sell their NFTs on various platforms and websites online that act in a similar way to Etsy or Amazon. These websites hold all the data relating to the NFT securely.
For investors, you can sell or trade NFTs. Of course, as with any investment you will need to know when the best time to sell is and factor in any kind of appreciation or depreciation of your NFT.
For many people, NFTs represent a fun but lucrative investment.
INVESTING IN NFTs - THE FUTURE
Although it is difficult to predict the future of NFTs, they are here to stay and experts predict that they will only increase in value and popularity. If wealthy investors continue to invest the NFT market will grow and move beyond gaming and art realms.
Investors looking for long-term investments that are likely to grow in popularity are drawn to NFTs as they have the potential to increase in value, quickly.For investors the main benefits are that NFTs provide the following:
- Proof of ownership
- Exclusive access
- Certifiable authenticity
- Marketplace efficiencies
- Safe blockchain technology
- Facilitate diversification
From a Sharia point of view, scholars understand that NFTs are still very much in their infancy. Any investor needs to ensure that no Sharia principles relating to assets and Islamic finance are breached. For example, investing in NFTs that operate within haram industries such as gambling, alcohol, or porn would be deemed impermissible under Sharia rules.
In the fast-paced and dynamic world of cryptocurrency and blockchain, staking is emerging as a popular way to earn passive income. This has led to discussions and debate about whether staking crypto is halal.
This article will examine the concept of staking and the considerations relating to whether it can be deemed to be halal.
WHAT IS STAKING IN CRYPTOCURRENCY?
In cryptocurrency staking occurs when investors lock cryptocurrency for a specific period of time. This is done to support the blockchain operation. The investor will lock in their digital tokens to a specific blockchain network and in return, they will earn rewards.
For the blockchain network, it means that transactions can be validated and for investors and individuals it means they can earn rewards without having to sell their crypto.
In comparison, bitcoin and staking are not linked. Bitcoin tends not to use the staking mechanism. Instead, it uses the proof of work mechanism where miners compete with each other to problem solve maths puzzles to validate transactions.
Any locked up cryptocurrency acts as collateral to support the blockchain network. This means that it is no longer available for use and therefore staking reduces the liquidity of the asset that has been staked for any given project.
HOW DOES STAKING WORK?
Crypto staking is a consensus-based mechanism. It enables token owners to validate a crypto chain by adding blocks. Using existing crypto to validate holdings as proof of stake on a blockchain.
Any newer blocks are also validated using the proof of stake mechanism. As the crypto funds are effectively locked in for a period of time this supports the activity of the blockchain. For the investor or asset owner who are using the blockchain platform, they earn staking rewards which are similar to earning dividends on their assets.
There are two main forms of staking:
- Independent staking : this method is used when an individual deposits their crypto token as a single and sole validator on a blockchain. There is usually a minimum token threshold. For investors using this form of staking they aim to benefit from being the sole beneficiary of rewards earned.
- Staking pools: staking pools are when there are a group of people who effectively pool their crypto tokens. This is the preferred method for newcomers to staking who want to share the risk with others.
Staking involves contractual terms that identify the obligations and the rights of the parties in the staking process. These terms can vary depending on the nature of the staking.
Sharia Compliance And Staking Crypto
Islamic finance provides the conceptual and foundational basis for operating financial transactions in line with Islamic rules. Operating in an Islamic finance framework means you use your finances to ensure you manage funds in an ethical and socially responsible way.
When considering crypto staking, it is important that you do all your due diligence. Investors or those staking their crypto need to understand the mechanism of staking and screen it for Sharia compliance. You need to fully understand what happens once you deposit your crypto onto a blockchain network.
In a proof-of-stake system, any crypto being staked is used to strengthen the consensus based network and improve the integrity of it. The profit is made from the rewards you receive for investing in the blockchain's sustainability.
Always make sure you understand the level of risk involved, the projects involved and the legitimacy of the network before staking your assets. A problem could arise if the blockchain itself is deemed halal but further down the line it starts to become involved in haram industries. Management of your crypto wallet should follow the same Islamic principles as your physical wallet. This requires ongoing due diligence.
Considerations
As a starting point, you need to ensure that the blockchain is not associated with any haram industries such as gambling, alcohol and pork. Look for morally sound initiatives and well-researched projects that have already been screened.
Another important point to consider is riba / interest. Whilst earning rewards via staking is not considered to be riba, examine the structure and payment of the rewards you will be generating. For many, staking a deposit is not seen as a loan so interest cannot therefore be generated. The reward is seen as the benefit of a joint endeavour, as more people join the blockchain, more rewards are achieved. The purpose of the stake is to improve the legitimacy of the network and to maintain it.
Another consideration is the governance and the values of the blockchain platform. Make sure that the governing values are ethically sound.
IS STAKING HALAL?
Consider all the advice in this article, but in particular, if you want to determine if any staking activity is halal you need to evaluate the halal status by ensuring:
- there is no interest / riba involved in the staking or the investment of any capital
- There is no excessive uncertainty or ambiguity - the terms required must be clear
- look for ethical compliance
- focus on asset backed transactions and stay away from gambling
- seek an expert opinion
- review the market the blockchain might be linked to and evaluate it for Sharia compliance
- review the other users of the blockchain
- make sure any incentive being offered is halal
- check the governance, infrastructure, platform and protocols being used
- learn all you can about your stake and the price
Staking in its traditional form does not currently involve any kind of loan or interest. There is no borrowing of money or any interest payment. Essentially, the software involved generates tokens as rewards. These rewards do not impact or come from any other users currency so there is no exploitation of others via investment or trading.
Practical Steps For Muslims Considering Staking
For anyone looking to stake crypto, it is essential that you seek guidance from scholars who are fully aware of Islamic finance concepts and principles when it comes to money matters. Look for blockchain platforms that are already established within Islamic networks.
Some of the benefits of crypto staking include having the opportunity to earn additional tokens (passive income). Also, as you are contributing to the security and efficiency of the blockchain network this could be seen as strengthening the decentralized platform for others.
Whether you are a beginner or seasoned investor, when it comes to halal investment this article will explain everything you need to know. This guide is your gateway to understanding Islamic finance, investments, assets, and the value of making informed investment decisions.WHAT CONSTITUTES INVESTMENT?
Investment refers to the process of buying assets with the aim of the assets increasing in value over time. As the value of the asset increases, the investor is provided with a return that takes the form of capital gains or income payments. Investment has historically always been associated with the growth of wealth and the pursuit of capital income. However, investments can also be a means to improving lives and the lives of those in your community.
Investing becomes profitable when the asset you invest in increases in value and you are then able to sell it at a higher price. When the asset increases in value this is known as appreciation.
Investment can be complex and fraught with risk and technical difficulties. Add in the Sharia rules and the world of halal investment can seem increasingly daunting for Muslims. Sharia compliant trading and investments are those investments that do not breach the Sharia rules which are based on the idea of ethical investment and saving. Islamic finance principles relating to finances and investment are based on social justice, non-exploitation, and halal investments that lead to a mutually beneficial partnership.
WHAT IS SHARIA COMPLIANT OR HALAL INVESTING?
Halal investment refers to the investment of money in accordance with Islamic finance principles. Sharia finance law is centred on the concepts of social justice, ethics, and using finances to help build communities. For any Muslim considering halal investment strategies, the focus should be partnerships that are mutually financially beneficial.
Sharia law lays down principles and regulations Muslim investors must comply with if they want to invest in halal products. According to Sharia rules, compliance with Islamic finance principles leads to a more ethical and just society. This goes against the western notion that making money is the ultimate aim for investors. Whilst Islamic finance does not prohibit making money, it does place emphasis on ethics and justice, so that a balance is achieved between religion, family, life, intellect, and property.
Halal investments should not be dismissed by those wanting to generate income. Islamic finance is not restricting or limiting, it simply proposes ethical practices and mutual benefit. Halal investments encourage Muslims to invest responsibly and always ethically. It is still very possible to make money ethically with the right investments. Investing within Sharia compliant products actually reduces the risk for investors, and is one of the reasons that Islamic banks were able to withstand the economic collapse in 2008.
Investment And Islamic Finance Principles
Islamic finance principles provide financial principles for Muslim investors to operate within to ensure that the financing and investment activities comply with Sharia law. Whilst the main principles of Islamic finance have been around for centuries, formal Islamic banking and finance was established in the 20th Century.
As the global Muslim population continues to grow, so too does the demand for Islamic finance products and banking. The Islamic finance sector is increasing in size every year, with Islamic finance institutions overseeing over $2 trillion.
The core difference between traditional investment and Islamic investment is that Islamic finance principles dictate what investments are deemed to be halal or not. Islamic finance needs to comply strictly with Sharia law, and the following Islamic finance principles are expressly prohibited:
Paying And Charging Interest (Riba)
Interest payments, or investments that include an interest element, are strictly prohibited in Islam. Charging interest is not considered to be Sharia compliant as it is deemed to be an exploitative practice.
Risk And Uncertainty (Gharar)
Sharia rules do not allow participating in contracts where there is excessive uncertainty or risks. Investing or partaking in any short-selling or uncertain contracts are forbidden in accordance with Islamic finance principles.
Investing In Prohibited Activities
For Muslim investors, investment in any business that is involved in prohibited activities such as gambling, and selling alcohol is prohibited.
Speculation (Maisir)
Sharia law prohibits speculation or gambling. So, if any form of investing includes contracts where the ownership is dependent on events in the future that are uncertain, this is deemed to be precarious.
Benefits Of Halal Investments
As the Muslim economy continues to increase year on year, the Islamic finance industry is also growing to cater for the need for growing halal investment options and products. Some of the main benefits of halal investments for Muslims (and no-Muslims) include the following:
- Social Responsibility - taking a socially responsible approach to finances and investment not only means the investment is Sharia-compliant, but it can also lead to human rights protections, just distribution of wealth, and ethical investments that minimise environmental degradation.
- Less Risk - Islamic finance principles mean that halal investment products are less susceptible to huge market changes and fluctuations. Global crises do not impact Islamic finance as they do more traditional banking. As short term speculation is discouraged in Islam, the exposure is much lower overall.
- Growing wealth in a halal way - this is the most critical benefit for Muslim investors. Not only does halal investment mean that Muslims can engage and involve themselves with global markets, it also means that Muslims partake in disciplined investment that requires ethical due diligence.
Stocks, Bonds And Shares
Stocks, bonds and shares are the most common publicly traded investments. Stocks are essentially ownership shares of companies that have publicly traded. A stock is a share of the companies earnings and assets, owning one stock is equivalent to owning a part of the company. If the value of the company increases then the value of the stock increases at the same rate. Similarly, if the market value of the company decreases then so will the value of the stocks owned. Muslim investors who purchase stocks will want to know the modus operandi of the company so that they can be sure that any income derived from their stocks is Sharia compliant.
Bonds are ownership shares of debt, and are usually interest-bearing. This means that the bond effectively acts as a loan to the company. On the whole, bonds are not considered to be a Sharia compliant investment as they are rooted in interest payments. Sukuks are a more acceptable form of Islamic finance bond (see below).
Gold
In terms of investment, gold is considered a safe and traditional means of investment that is Sharia compliant. Gold often appreciates in value, is easy to obtain and invest in, and is not deemed to be in breach of any Islamic finance laws.
Sukuk
Sukuks are an alternative to traditional bonds as they do not bear any interest. They are often referred to as Islamic bonds, and are normally asset based. They are deemed to be conservative investments on the basis that they form part of the 'fixed income' market.
Sukuks are able to generate income for halal investors without breaching the Sharia rules.
Property
Investing in property is a great way for Muslims to invest. The only caveat is that if a mortgage is obtained it is deemed to be a halal mortgage without any element of riba.
Prohibited Industries
Any halal investment must be in accordance with the Sharia principles mentioned above, and must be done with consideration of ethics and social justice. Companies whose main business goes against the central tenets of Islam are considered universally unacceptable as investment opportunities.
There are certain industries that are deemed to be unethical or at risk of causing harm to society, and Muslims should therefore avoid opportunities in these sectors:
- Industries manufacturing, promoting, advertising, or selling alcohol
- Industries manufacturing, promoting, advertising, or selling cigarettes or drugs
- Banking products or financial transactions that include interest (riba)
- Any industries related to gambling
- Industries related to prostitution or pornography
- Industries relating to pork
Sharia law prohibits investing in industries and businesses where at least 5% of their income comes from unethical sources (this is known as the 5% rule). Before investing in any business, Muslims should check out the financial statements and positioning of the company and do some research on their sources of income and profits and where they are derived from.
Halal Investment - What To Look For
When undertaking due diligence prior to investing, you should consider the following 3 types of investing opportunities:
1. Companies with halal practices - these are known as clean companies (from a halal investment perspective) and are companies that operate in a completely halal way. These companies operate within the Sharia finance rules, and have a clear halal audit trail.
2. Companies with haram practices - these types of companies operate within prohibited industries such as gambling and alcohol.
3. Mixed companies - these companies may have halal practices but these are mixed with haram practices or activities.
For halal investors, option 1 is always the best option as there is no overlap of the halal-haram considerations. Companies that have a cross-over between halal and haram should be avoided.
As one of the fastest growing finance sectors, Islamic finance has opened up many opportunities for halal investors. In the UK alone, there are many banks that offer specialist investing products, loans, and savings accounts.
Conclusion
Islamic finance promotes the concepts of ethical financial management and investment and reciprocal profits. The use of interest, risky investments, and unethical industry investment is discouraged. Halal investing is a growing financial niche, and it is available for Muslims and non-Muslims alike. Investing in products that are Sharia compliant is not difficult or impossible, it just requires some information gathering and due diligence.
Prominent private equity institutions like Gobi Partners have realised the growing demand for halal financial products. Over the last decade, more and more financial institutions and foreign exchange markets have taken steps to place themselves in the Islamic finance and private equity market. High net worth individuals in emerging markets such as Africa and the Middle East are entering the private equity investment market rapidly and this has led to an increase in demand for Sharia compliant investment opportunities. Islamic finance is no longer considered to be a niche and exotic sector within the banking industry.
Of course, the most important factor behind the growth of the Islamic finance industry is that Muslims make up almost a quarter of the world's population. The Muslim investor base is large and it is growing. This growth has not been lost on wealth managers and banks who are keen to tap into the wealth and investment funds in the hands of wealthy Muslims. Coupled with the economic expansion of many Muslim countries, it is likely that halal investment products will become more accessible within the next 10 years.
As the Islamic finance sector continues to grow annually, a faith-based approach to investing and trading is becoming more mainstream. However, the application of Islamic finance to investment products needs to be undertaken and can be nuanced, so always make sure to check the financial information of any company you are considering investing in.
Stay informed on finance
