
Islamic Wills

Wills
A will is a legal document that sets out the wishes of a person with regard to the distribution of their wealth, income, and assets once they pass away. An Islamic will is a will that documents how your wealth, property, and gifts will be distributed when you die and is prepared in accordance with Islam and Sharia law. The last will and testament specifies exactly what happens to your assets and wealth when you die. What you leave behind is known as your estate, and this inheritance will be passed down to those mentioned in the will upon your death.Islamic wills are also known as wasiyyah, and are one of the many important elements of Islamic financial planning.This article will discuss Islamic wills, why they are important, and how to ensure you have one prepared.
Wills In Muslim And Non-Muslim Countries
Islamic wills are used by Muslims who want to ensure that their finances and responsibilities are dealt with in a Sharia compliant way once they have passed. In Muslim countries, the rules of the country dictate the laws of intestacy, which is the law that will apply on the death of a person.
However, in non-Muslim and western societies (such as the United Kingdom) where Sharia law does not apply, Muslims look to having an Islamic will in place before their death to ensure that it complies with their Islamic obligations and the rules stipulated in Islam when it comes to inheritance.
Why Islamic Wills Are Important
For Muslims, it is critical that they have an Islamic will in place before they pass away. Not only is the importance of having an Islamic will highlighted in the Quran it is also mentioned in the hadith.
If a Muslim does not have an Islamic will, this means that their property and wealth will not be distributed in accordance with Islamic Sharia rules and regulations.
Islam places great emphasis on making sure you live your life in an orderly manner, and this duty for orderliness and preparedness also applies to leaving this world.
If a Muslim dies without having made an Islamic will then they should expect their wealth to be distributed by the rules of intestacy of the country they live in. In the UK and the United States, the rules of intestacy are not in line with Sharia rules and are therefore not Sharia compliant.
Importance Of Having An Islamic Will
It is especially important to have an Islamic will for those with dependants, a spouse, children, or other beneficiaries. Not only will an Islamic will deal with the distribution of your assets, it will also ensure that any charitable donations you wish to make are dealt with, but your family is provided for adequately, and your funeral is managed in line with your wishes.
It is always best to make your Islamic will as early as possible, and whilst you are of sound mind.
The incentive in doing this is that once you sort your will it can remain in place until you die unless of course you decide to make any changes in which case your Islamic will can be updated.
Dying Intestate
If you die without a will in a non-Muslim country then the intestacy rules of that country will apply. For example, in England, if you have no surviving relatives then your estate will automatically pass to the Crown.
Dying intestate not only means that your assets will be distributed without your instructions, but it also makes dealing with your estate long-winded and difficult. It can also take months and sometimes years to unravel the estate and distribute the assets.
Usually, a close member of the family such as a spouse or parent has the legal right to distribute and manage the estate and the real property within it.
Islamic Wills Explained
An Islamic will is a legal document that will outline how a Muslim's assets will be distributed on their death. What sets the Islamic will apart from the traditional will is that the Islamic will is drafted based on the guidance and rules set down by Islam and Sharia law.
The Islamic will not only deals with the distribution of your assets but should also cover what happens to your debts and monies you owe to third parties.
Islamic wills should always comply with Islamic laws of inheritance, this is why you need to use the services of a solicitor who understand Sharia law and compliance.
Islamic Laws Of Inheritance
Islamic laws relating to inheritance are set out in the Quran and the teaching of Prophet Muhammad (peace be upon him).Some of the main principles of Islamic inheritance laws are as follows:
- Equality - a key component relates to equality between female and male heirs. Sharia rules state that male and female heirs should receive equal shares in the estate of the deceased
- Differentiating between debt and assets - debts and assets should always be separated and any debt should be settled before any assets are distributed to heirs and beneficiaries
- Shares - Islamic rules and guidance states that there are certain heirs (such as husband / wife/ children) who are entitled to what is considered to be a mandatory share of the estate
- Beneficiaries and heirs - for those writing and preparing wills, they should be mindful of the determination of heirs. That is those heirs who are specifically entitled to a share in the deceased estate (this includes spouses, children, parents, and grandparents)
Requirements Of Islamic Wills
When it comes to Islamic wills there are some key principles you need to be aware of:
- Compliance with Sharia law - make sure you know and understand the intestacy rules of the country you live in. Do not just assume that Sharia rules apply, do your due diligence and make any relevant inquiries
- Finding the right professional - when it comes to writing the will you should always seek the services of an Islamic lawyer who understands Sharia rules and the Islamic distribution of assets. The cost and expense will likely be the same as appointing a non-Muslim probate solicitor.
- Writing the will - the wording in the Islamic will should be clear and concise with no room for ambiguity or uncertainty
- Signing the Will - make sure your signature is applied in the right place and witnessed by two credible, Muslim witnesses. The last thing you want is for your will to be challenged in the future.
- Review - once your Islamic will has been prepared and signed you should review it periodically to make sure it still meets with your requirements and wishes.
Why Islam Recommends Having An Islamic Will In Place
There is a huge emphasis in Islam for Muslims to have an Islamic will. Ensuring that our assets and property are distributed in accordance with Sharia principles is the last legacy for Muslims before they exit this world and enter the next.Every Muslim will want to leave this world and leave their estate in a way that pleases Allah.
Benefits Of Islamic Wills
For Muslims, the main benefit of an Islamic will is that it ensures the estate is distributed in accordance with Sharia rules.Let's have a look at the main benefits of having an Islamic will prepared:
- Islamic estate planning - as mentioned above, there is peace of mind knowing your estate will be managed as per your wishes
- Islamic compliance - Islamic wills are Sharia compliant
- Avoids disputes - having the Islamic will prepared means that disputes about the distribution of your assets in the future are minimised
- Protection for heirs - of course, having the will ready means that your beneficiaries are protected and your assets, property, gifts, and money are shared in accordance with your wishes
- Burial - your Islamic will can outline plans for your funeral and burial and make sure it is all done in an Islamic way and in accordance with your belief and choice. This not only gives you reassurance but also makes the whole experience easier for those you leave behind.
In addition, Islamic wills can also address the importance and appointment of a legal guardian when minor children are left behind. Islamic law states that a legal guardian should be appointed in accordance with the best interest of the children.
Islamic wills can deal with such appointments, and this means that your son or daughter will be adequately supported by your nominated guardian.
ISLAMIC WILLS - WHAT IF THERE IS A DISPUTE?
If you find yourself in a situation where there is a dispute relating to an Islamic will then the first thing you should do is seek the services and advice of a professional Islamic wills lawyer.
Your lawyer will be best placed to advise you of your options, and many of them offer telephone call consultations and advice. If the dispute cannot be sorted via discussion and negotiation with the other parties involved, then you could seek a resolution through the Islamic Sharia court system.
Sharia courts are able to deal with disputes and help resolve disputes in accordance with Islamic principles.
What you should remember though, is that having a well-drafted, water-tight Islamic will means that it is less likely to be challenged or to lead to disputes in the future.
A good professional solicitor with knowledge of Sharia principles will help you prepare your Islamic will and ensure that it meets your requirements and remains Sharia compliant.
You should also make sure you speak to a financial expert who can advise you about tax planning making sure your property, assets and money are distributed in the most tax efficient way. Inheritance tax rules differ from one country to the next so it is always important to understand how they will impact you.
In addition to this, you should also consider having an executor you trust and who will abide by your wishes. The executor could be your solicitor, your child, or your parent, sibling, husband or wife.
Always be conscious of the fact that the rules about inheritance laws vary from one country to another, so always make sure you have the correct information you need. Seek the advice and opinion of a lawyer who specialises in Islamic Sharia law and Islamic wills.
Receive insights on ethical financing and Islamic finance directly to your inbox.
Explore more news
The growth of Sharia-compliant finance services has led to a similar growth in technology that is advancing and supporting sharia compliancy for businesses. Sharia-compliant fintech has emerged as driver of innovation and ensuring businesses can operate efficiently and within the rules of Islamic finance.
By leveraging technology, Sharia-compliant businesses are able to operate in a compliant way whilst also ensuring they are not left behind in the fintech revolution.
In addition, businesses can use technology to offer their clients and customers opportunities to become more engaged in socially responsible and ethical financial activities.
Technology that supports Sharia-compliant businesses to operate also supports Islamic finance principles relating to money, financial transactions, and any form of investment.
WHAT IS SHARIA-COMPLIANT TECHNOLOGY?
When we talk about Sharia-compliant financial technology (fintech), we refer to technological solutions that adhere to Islamic finance rules relating to Sharia-compliant transactions and services.
The fintech can take the form of online tools or cutting edge technology that includes artificial intelligence, blockchain, online banking, Sharia compliant banking, and apps that support Muslim businesses.
Sharia-compliant technology needs to ensure it is:
- Compliant
- Transparent
- In accordance with Islamic finance rules
- Accessible
Technology that is Sharia-compliant plays a critical role in ensuring that Muslim businesses can expand their reach and continue to grow. For many years, Muslim entrepreneurs and SMEs in the West had no alternative to the conventional form of finance structures offered by Western banking services.
These services and products were mainly not compliant with Sharia rules as they relied heavily on interest based lending (riba) which is strictly prohibited in Islam.
With the advent and growth of Islamic finance, the fintech industry has developed many different types of technology to support businesses and customers who want to carry out business transactions whilst remaining true to their Islamic principles.
The Intersection Of Ethics And Fintech
The combination of technology and ethics is a key component of Sharia compliant finance. Islamic finance rules are underpinned by concepts of social justice and ethics, and it therefore follows that technology must also play its role in implementing and amplifying ethics.
Leveraging technology within Islamic finance via fintech platforms and services means that businesses are increasing their ethical standing and social responsibility.
Sharia compliant fintech platforms and products needs to ensure that interest is prohibited, excessive uncertainty or ambiguity is avoided, and there is complete transparency. What technology facilitates within the Islamic finance sector, is efficiency, broader accessibility, and transparency. These are all key ethical concepts within the Islamic finance framework.
Smart contracts and decentralised platforms lead to greater accessibility and efficiency. They take the control away from large organisations and ensure that previously excluded financial groups can partake in business, whether as owners or customers.
Fintech Solutions
Technological solutions enable automated compliance, increased monitoring, reporting, real time tracking, and enhanced risk assessment and mitigation. These all align with the ethical values of Islamic finance and Sharia rules.
As technology and fintech solutions continue to evolve and come to the market, they are playing a crucial role in the accessibility of Sharia-compliant business finance. This is done through technology that enhances transparency, accessibility and offers innovation.
Let's have a look at some of the solutions that enable businesses to operate in a Sharia-compliant way:
- Smart contracts: smart contracts facilitate automation and transparency for all parties and therefore reducing any risk of exploitation and future disputes.
- Blockchain: blockchain technology is centralised this means control moves away from the conventional bank model and market. Blockchain also reduces the risk of fraud.
- Digital banking: online banking platforms have not only introduced global audiences to more finance options, but these platforms are often user friendly and Sharia compliant. Customers and businesses are able to access current accounts, business accounts and financial solutions at the press of a few buttons.
- Crowdfunding: these platforms are fast emerging as a Sharia compliant form of raising capital and investment. Our Sharia-compliant investment guide explains more about how these funding routes work and what to look for. Many Muslim businesses and ventures across the world have created crowdfunding campaigns when they have not been able to find Sharia-compliant funding options for their project.
-
- AI: the future is definitely becoming more automated and managed. When it comes to the financial services economy, it is fair to say AI has the potential to revolutionise the products and services that already exist.
- Regulation tech (Regtech): for many Muslim businesses including those in the healthtech sector (dentists, pharmaceutical companies, health centres) regtech is critical. Not only does it ensure regulatory compliance, but is also essential for monitoring and maintaining Sharia compliancy.
Islamic Fintech And Social Innovation
The basic principles that underpin Islamic finance are rooted in financial stability and security. For businesses, this includes an element of corporate social responsibility. The advances in technology mean that fintech has provided businesses with the ability to compete on equal or better ground than those operating in the conventional banking system.
Technological innovations including online banking platforms have enhanced compliance with Sharia law. For example, online platforms have led to increased:
- Transparency
- Accessibility of Sharia compliant products
- Automation of compliance monitoring and reporting
- Secure transactions
- Educational information
- Customised Sharia-compliant solutions
Technology For Businesses And Individuals
It's not only businesses that are benefiting from compliant fintech solutions.
Consumers and customers are also becoming deeply ingrained in new and innovative digital ecosystems. Just consider how many people use online banking apps to monitor their spending, make obligatory payments such as zakat and sadaqa online, or donate their accrued interest payments in halal ways.
For businesses within the health sector such as dentists and pharmaceutical organisations, technology has enabled them to operate in a Sharia compliant way.
Technology aids businesses to plan their strategy whilst also ensuring they continue to adhere to Islamic finance principles.Technology is used to improve accuracy and efficiency by providing real time data. Sharia compliance can often be automated within the technological systems those in the health sector use.
Crowdfunding
For new businesses, entrepreneurs, and those with creative ideas, finding the appropriate finance to fund their ideas and projects can be difficult. It is even more difficult for those who are looking for funding options that are Sharia compliant. Without the necessary funds, creating a successful business or launching an idea is near impossible. Crowdfunding has emerged as a great way to raise capital and find the financial backing you need.
For Muslims, crowdfunding can be viewed as a halal way to raise funds, without having to resort to conventional funding options which are interest-based.
Crowdfunding facilitates economic growth for many companies, startups, medium enterprises, and individuals. In return for the investment, investors aim to receive a return from the profits generated.
This article will examine what crowdfunding is, who benefits from it, why more and more Muslims are using crowdfunding platforms, and what you need to look out for if you want to keep your money halal.
Basic Concepts Of Crowdfunding
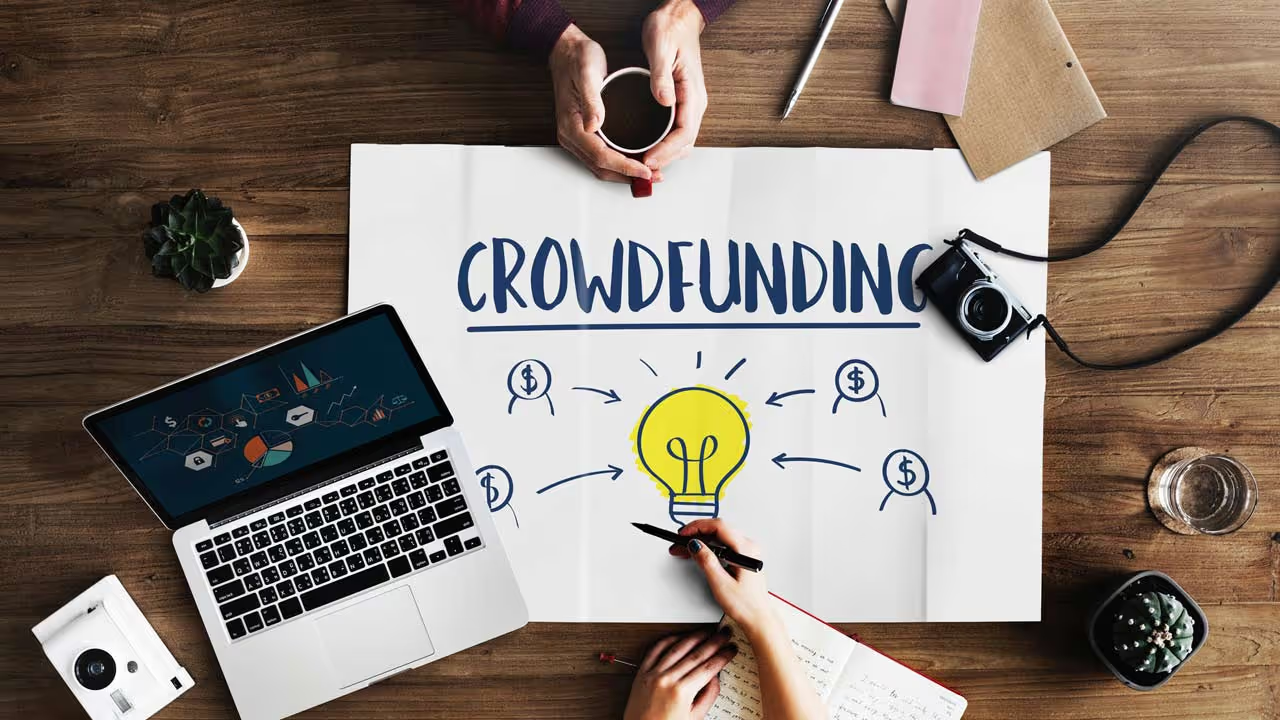
The very basic concepts of crowdfunding revolve around raising funds from a crowd of people - hence the name crowdfunding. Essentially, it is the crowd that funds the project.
This is an alternative to going to a bank for a loan and securing funding that is essentially a debt.
Some of the key concepts that crowdfunding is based on include:
- the project: a creator or company starts the crowdfunding campaign based on a project or idea. The idea is presented via the online crowdfunding page coupled with a request for for investment and financial backing.
- the platform: the crowdfunding platform is the means by which creators are connected to the angel investor, venture capitalists, potential donors, investors, companies, and backers. Some popular crowdfunding platforms include Indiegogo, GoFundMe, and Crowdfunder.
- Investors: the investors or backers are the individuals or companies that contribute funds to the campaign. In return, they can either receive rewards, equity or just the satisfaction of knowing they have made a contribution to a campaign they believe in.
You can see why any startup company or entrepreneur would look to crowdfunding as a viable way of raising funds.
A crowdfunding campaign should include full details of the project and present it well on the relevant platform or website. The details should be precise and include:
- the project details (including the industry, the market targeted, services on offer)
- the funding goal
- what the money will be used for
- timeline of the deal
Conventional Crowdfunding Types
Some conventional crowdfunding types include the following:
- Donation based crowdfunding: this is where donors contribute to the campaign without expecting anything in return. Many charitable causes raise money this way, but it is also used by individuals for personal fundraising.
- Reward based (equity crowdfunding): this type of crowdfunding is when backers contribute funds to a particular project in exchange for non equity rewards. These can include incentives, early access offers, or special merchandise.
- Debt based crowdfunding: this is the type of crowdfunding where backers lend money to the crowdfunder on the understanding that the money will be repaid (this usually includes interest repayments).
Crowdfunding - Islamic Finance
Some of the basic Sharia rules relating to finance must be complied with if any crowdfunding campaign is to be considered halal. As a financial model, Islamic finance has been successful for many decades. Not only does it facilitate financial inclusion for marginalised communities, but also ensures that small and medium sized businesses have accessible finance.
Islamic crowdfunding aligns with the ideals of Islamic finance, with the focus on the development of society and individuals whilst meeting Sharia goals.
Conventional finance and management has not been able to support small and medium Muslim businesses in the way that crowdfunding has. This is because conventional financial transactions relating to funding are based on interest and debt repayments. For Muslims, this is a price they are not willing to pay.
Crowdfunding is a public-private collaboration, and when done in a Sharia compliant way, it can offer Muslims a viable way of raising money whilst also delivering economic growth.
In fact, crowdfunding as a concept is not unfamiliar to Islamic finance. The current crowdfunding concept can fund its roots in the concept of Islamic microfinance which aims to bring social justice and equity into financial transactions.
IS CROWDFUNDING SUITABLE AS A HALAL FORM OF FINANCING?
To answer this question we need to examine whether crowdfunding can be compliant with Sharia rules, and what Sharia rules state in relation to crowdfunding. Crowdfunding at its very essence is a social collaboration idea, and this fits with Islamic finance principles.
The idea is that individuals collaborate and donate resources to a project, service, or trade that they believe in. With Islamic finance's emphasis on equitable wealth distribution, crowdfunding certainly meets this focus.
Wealth distribution in a fair way is a core principle of Islamic law, and what better way to flow funds from one person to another than crowdfunding. Crowdfunding enables the public to help private sector companies and individuals to grow their enterprises in a socially responsible way.
Another important aspect of Islamic finance to mention here is the focus on ethical responsibility and profit and loss sharing (risk taking). This is pretty much what crowdfunding does. It allows companies and individuals to share in the risks being faced as well as the opportunity to share in the rewards and returns that are generated.
Of course, not every form of crowdfunding model is halal. For example, any form of crowdfunding that includes interest payments or haram industries or enterprises is not permissible and not Sharia compliant. In fact, any crowdfunding model involving interest or speculation is prohibited.
It is important to ensure you do your research and find a project and platform that works within the parameters of Islamic finance rules.
Islamic Crowdfunding
Islamic crowdfunding enables investors to support small and medium businesses in their economic activities via a distribution of wealth. Look out for projects that have an element of social and economic justice attached to them.
There are many crowdfunding projects out there which aim to relieve poverty and to provide financial aid to the poor based on charitable donations and these projects always do well.
Mudaraba contracts can be used in Islamic crowdfunding. They work on the basis that:
- profits from the projects are distributed between the creators and the investors.
- predefined percentages are used in relation to profits
- Investors do not influence the project or have veto powers
- the contracts are beneficial for startups with innovative ideas
In addition, having a zakat based crowdfunding project would also be a concept that is compliant with Sharia rules. Those in need of zakat can set up campaigns asking for zakat money or charitable donations.
Sharia Rules And Regulations
As already mentioned, any crowdfunding project must be Sharia compliant if it is deemed to be in accordance with Islamic finance rules. This means:
- the project, goods, or services must not be involved with any haram industries (porn, alcohol, gambling).
- the capital used to finance the project must be halal
- no interest can be paid or charged
- a Sharia supervisory review should be in place to monitor and track the crowdfunding campaign
Challenges For Those Offering Islamic Crowdfunding
Despite their popularity, crowdfunding campaigns also have their own unique challenges.
Some of the challenges include:
- Generating public interest: one of the main reasons crowdfunding campaigns fail is that they do not generate enough interest from people. Getting the attention of potential funders and investors is key to a crowdfunding campaign.
- Trust: with so many crowdfunding campaigns live at any given moment, some investors shy away from crowdfunding. Before you try and raise any money via crowdfunding, it is important to be able to tell the story of the project and why funding is needed.
- Ideas protection: as with anything these days, once a crowdfunding campaign does well, 10 similar projects will come forward. When presenting your project on any platform you need to ensure that you provide enough information to garner interest from backers, but also keep enough back so you can protect your idea.
- Risk management: as Sharia rules state that profits, losses and risks should be shared equally it is important to ensure that the crowdfunding arrangement meets these goals.
- Technology: in many countries around the world, electronic payment methods are still not common. This means crowdfunding still has limited availability to the poorest in our society.
Overcoming Challenges
The best way of overcoming the challenges relating to crowdfunding is to make it more accessible. By its very definition, crowdfunding is a concept that relies on the crowd to forward fund projects.
Due to the importance crowdfunding places on sharing and participation, crowdfunding platforms across the world are demonstrating cultural and social benefits. As a new platform, there is still more regulation and development to come, but for Muslims it is an innovative approach to raising finance in a halal way.
One of the most fundamental points to remember with crowdfunding is that crowdfunding itself is not automatically deemed to be halal. Each crowdfunding investment opportunity of project needs to be evaluated by the investor or creator to make sure the investment complies with Islamic finance rules.
In addition, the crowdfunding platform and the project need to be assessed on an ongoing basis. Do not assume that once a project starts it will remain halal. Muslims who want to use crowdfunding to raise funds or to invest must ensure that they continue to ask questions, undertake due diligence and consult with scholars and financial advisors who understand Islamic finance.
With the financial landscape changing constantly, Muslims are looking out for investments that are profitable and Sharia compliant. With so many Muslim women managing their own finances and the finances of their home, there is an increased demand for halal investments.
Making spiritually aligned investments seems more important than ever in todays society.Whether it is investing in the stock market, the exchange-traded fund, personal savings, having an ISA or looking to invest in real estate, more and more Muslim women are looking for smarter ways to invest.
So, what are the things you need to look out for when considering halal investment? Let's take a look.
Understanding Halal Investments
Halal investments are those financial activities that are compliant with Islamic finance rules and Sharia law. Islamically, financial dealings which are based on interest or speculation are not permitted. This means many Muslims will not invest.
Islamic finance investments are more focused on investments that are ethical and deemed to be socially responsible. That is, they offer some tangible benefit to society and are not exploitative or speculative.
For an investor looking for a halal investment, they need to look out for the following:
- the investment must avoid any form of interest: charging or paying interest is haram in Islam. This means that if you are investing in an industry that includes interest or is deemed to be a haram industry then this is not permitted.
- the investment should avoid any kind of ambiguity: this means that any form of investment in stocks and shares that is akin to gambling is not allowed. There must be clear terms and conditions and transparency in all transactions that relate to any asset or money.
- It is important to avoid haram: this relates to any industry or dealing that is haram.
- social responsibility: it is important to ensure that any investment aligns with your ethical responsibilities under Islam and is socially responsible. To invest in arms production would not be deemed to be halal, nor would investment in the alcohol industry.
Navigating Financial Products That Are Halal
Halal investment can take many different forms. They include the following:
- Islamic banking: banks and other financial institutions often offer services and products that are halal. You can use a Sharia compliant bank account to save your money.
- Islamic mutual funds: these kinds of funds have been vetted to ensure they are Sharia compliant (although you should also make your own enquiries). Islamic mutual funds invest in Sharia compliant industries, markets, and assets. Investors share in the profits generated and also in the losses if they occur.
- Islamic real estate: investments in real estate are becoming more common with the onset of Islamic finance mortgages and funding options.
- Islamic bonds (sukuk): Islamic bonds are the type of financial instruments that are fully compliant with Sharia law. They offer investors ownership in an asset and the profits and revenue are generated by the asset.
- Halal stocks: companies that operate in a halal way offer stocks that can be purchased by investors.
- Exchange-traded funds: you can find halal ETFs on the market if you look carefully. There are many ETF products that invest in a range of halal stocks and other permissible assets.
- Islamic crowdfunding: some platforms are now offering Islamic crowdfunding options and peer lending options from one person to another. If thinking of making an investment on such platforms make sure that they are Sharia compliant.
Empowering Women
There are growing numbers of young professional women who want to invest and manage their money in a Sharia compliant way. For these women investing in halal companies and stocks is not simply about wealth management but also about adherence to the rules of Islam.
The empowerment of women in the financial sector has always been a practice in Islamic societies. The very fact that women often manage the household finances and then have to ensure they have sufficient funds for the charitable payments of zakat, means that women have always been financially literate.
In Islam, mutual consent in financial dealings is one of the central concepts of Islamic finance. This has meant that women have been involved in decisions about payments and finances from the start.
Women And Business In Islam
Historically, Islam has always promoted the independence of women whether that is in the fields of education, trade, and finances. Historical accounts document that Muslim women were engaged in trade and business many centuries ago. For example, the wife of Prophet Muhammad (PBUH) was a very successful businesswoman.
Islam has always had legal protections in place for women to protect and grow their finances. These protections have secured Muslim women's rights in marriage, in inheritance, and in succession.
Halal investing is linked to faith and encourages Muslim women to view their wealth as a blessing from God and one that needs to be shared and stored ethically. In Islam, women and business are not mutually exclusive. In fact, Islamic history teaches us that women have always been active participants in the business world.
Islamically, women are entitled to own, invest and manage their own funds.
Explaining Interest-Free Finance
For anyone looking to manage their finances in a Sharia compliant way, the very first step is to ensure you are not charging or paying any form of interest.
Interest free finance operates without including interest in financial transactions. When it comes to investing, it is important that you stay away from interest and any industry that relies heavily on interest or debt based finance.
Interest is seen as very exploitative and unethical.
Interest free finance operates on the basis that both parties to the transaction share the profit and the risk. The focus is on real economic activity that generates profit, rather than using money to create money via interest.
Educating yourselves on the core concepts of Islamic finance will ensure that any investment activity you take part in will be Sharia compliant.
Define Goals And Objectives
Identify what your financial goals and objectives are. Look for a market that appeals to you and aligns with your personal values. This should also apply to other forms of investment such as your pension. Is your pension being invested in companies that align with your ethical position? Always do your due diligence and research the industries your finances are involved with.
Spread your investments. Diversify your portfolio as this will not only reduce your risk but enable you to do more social good with your money. It is not necessarily always the case that investing in one kind of stock or bond will yield the best results.
Look at halal index funds and examine the market of each fund. How do they operate? Where do they operate? what information do you have about the return you will receive? Is the service being offered Sharia compliant? what practices does the industry use? How do they pay?
If any industry is non-compliant with Sharia rules then stay away from it.
The value of your investment should not be based on speculative activities or interest. This applies to any form of investment and savings accounts.
Choosing The Right Provider For Halal Financial Services
It is essential that you consult with Islamic finance experts and scholars if you are unsure of investing. An educated Islamic finance expert will ensure that your investment choice is Sharia compliant and regulated properly in the UK.
Once you have made the investment you must undertake periodic evaluations. Regularly reviewing your investment portfolio will ensure it continues to align with your ethical and financial goals. Don't assume that an investment will remain Sharia compliant throughout its lifetime. Companies change course depending on the economy so keep an eye on the Sharia compliancy.
Aligning Values With Ethics And Wealth
When it comes to aligning values with ethics and wealth, Muslim women are embracing the principles of Islamic finance and Sharia compliant investment. Whilst Islam is centred around the the 5 pillars (declaration of faith, prayer, charity, fasting, and hajj pilgrimage), Muslims are also expected to follow the Sharia.
Pursuing halal investment and savings not only ensures that you live a Sharia compliant lifestyle, but also ensures that you live a more meaningful and ethical life.
It is essential to educate yourself and gain an understanding of Islamic finance principles. Stay informed about the different financial instruments that are available and assess them for compliance with Islamic principles. Screen investments and work with companies who also align themselves with Islamic finance rules.
The world of Islamic finance based investments is widening year on year, so there are plenty of options available out there. Regularly review your investment portfolio and make any adjustments you need to. Finally, be patient and be ethical.
Qardus do not provide financial or investment advice.
Stay informed on finance
