Commodity Murababa For Business | Sharia-Compliant

Islamic Finance provides a financing mechanism without Riba (interest), Gharar (gross uncertainty) and Maysir (gambling). These three are the key to all economic oppressions, economic imbalances and instability. They give rise to micro and macro risks which impact the overall wellbeing of an economy. Islamic Finance offers alternative structures and products which are free from Riba, Gharar and Maysir. One of these products is Commodity Murabaha.
In minorities where it is difficult to get Shariah compliant working capital financing for SMEs, Commodity Murabaha is an alternative Shariah compliant product and financing mechanism. Commodity Murabaha is the most common Islamic money market tool that is used to provide liquidity in the short-term Islamic money markets. The AAOIFI Shariah Standards, the majority of global Shariah scholars and global Shariah boards approve of Commodity Murabaha if it is implemented correctly with the correct controls to overcome financing challenges. The classical jurists also approved of a Tawarruq or Commodity Murabaha structure. In fact, Mufti Taqi Uthmani has produced a detailed research paper on Commodity Murabaha outlining the views of classical scholars. Ibn Muflih from the Hanbali school, Imam Shafi’i, Ibn al-Humam and Ibn Abidin from the Hanafi schools have all permitted this product and narrate its permissibility from other classical jurists[1].
Working capital financing is used to cover a company's short-term operational needs and not to buy long-term assets or investments. Those needs can include costs such as payroll, rent and inventory and other costs associated with daily operations etc. Practically, business owners who are looking for shariah-compliant working capital financing to cover their short-term operational needs generally prefer entering a Commodity Murabaha Agreement where a fixed profit rate and corresponding deferred sales price instalments is specified in advance. This allows them to finance their growth at a lower cost of capital as compared to for example using profit and loss sharing (PLS) arrangements such as Mudarabah and Musharakah that result in a higher effective cost of capital. PLS arrangements are better suited for business ventures where there is a higher risk of loss. Profit and loss sharing refers to financing whereby parties enter into equity financing arrangements where the financier has a share ownership in the business.Furthermore, a stable business looking to finance their working capital might not want to dilute their ownership through equity financing. Stable businesses will not want to share their upside so would prefer debt-based financing. By doing so, they are happy to protect the financier from the downside and retain exclusivity to the upside. A PLS is favourable where there is greater risk of downside and therefore the business is happy to share the upside.
In the UK, the most direct and common way for a party to obtain working capital is to obtain an interest-bearing loan from a third-party finance provider. Since a conventional loan represents a purely monetary transaction—in essence, the use of money by a party in exchange for the payment of compensation based on the length of usage—this type of loan may not be given or received by Shariah-compliant investors. The Commodity Murabaha product allows Muslims to finance their working capital without being exposed to interest-based financing.
The Commodity Murabaha agreement has been conscripted to fill the void. A customer enters into a Commodity Murabaha transaction not to obtain a physical asset for its use, but to engage in a series of purchase and sale transactions that result in the customer obtaining working capital. In a basic Murabaha transaction, the customer receives assets in return for a deferred payment obligation, and then employs those assets in its business. In a Commodity Murabaha transaction, the customer takes the additional step of selling the assets to a third party for cash, which represents the working capital (or financing for an acquisition, as the case may be) required by the customer. Note that the customer would not necessarily be required to sell the Assets to a third party; it merely is allowed to do so, as owner of the assets. The sale of the assets to a third party is not an element required to make the Commodity Murabaha transaction a valid transaction under Shariah.
To ensure that this product is not a smokescreen for Riba (usury/interest), contemporary Shariah scholars have placed several controls. The AAOIFI Shariah Standard highlights these controls to ensure that Commodity Murabaha aligns with the principles of the classical jurists. These controls are as follows:
- Different brokers: The trades must involve the market and involve different brokers from the buy and sell side. This ensures that the trades are genuine and that the brokers are selling/buying the asset with an interest in the asset.
- Real asset :The trades must involve a real asset. A fictitious product cannot be sold. The asset transaction must impact the inventory of the seller and the eventual buyer.
- Real trades: All the Shariah requirements for trading must be met in terms of valid offer, acceptance, legal capacities of the parties, agreement on the commodity, agreement on price etc.
- True ownership: The traders should assume true ownership through true sales of the underlying commodity.
- Possession: The traders must assume possession; either physically, constructively or digitally. This possession must allow them to dispose of the asset or redeem the asset.
- Correct Sequence: The Commodity Murabaha must be performed in a correct sequence which further establishes and validates all of the above key elements.
- Discretion to not sell: The traders must have the discretion to not sell and hold. This ensures that the trade is not fictitious.
- Different agents: The financier should not be the sole agent for all the parties involved in the Commodity Murabaha.
By meeting the above principles, the Commodity Murabaha is a Shariah compliant, asset-backed financing mechanism which aligns with the principles of Islamic Finance. From a micro-economic perspective and for a Muslim minority in the UK context, this product provides a valid Shariah compliant alternative in a system where every corner and every offer are interest-based. An overview of the Commodity Murabaha facility used by Qardus for SME business financing can be found here.
You can contact Mufti Faraz Adam on sharia@qardus.com
[1] Uthmani, M.T. (1998), Buhuth Fi Qadhayah Fiqhiyyah Mu’asarah. Dar al-Qalam
Receive insights on ethical financing and Islamic finance directly to your inbox.
Explore more news
WHAT IS INVESTMENT BANKING?
Investment banking refers to a form of banking that deals with large and complex financial transactions. These transactions include mergers, acquisitions, raising capital funds, and re-organisations of businesses.
Investment bankers work with clients within the world of investment and high finance. Investment banking often deals with raising funds and money for large companies and governments.
Investment banking also involves underwriting debts and securities and brokering trades for private and global investors.
As conventional investment banking includes many interest-based and speculative activities, this has raised the question about the permissibility of investment banking in Islam and if it is haram.
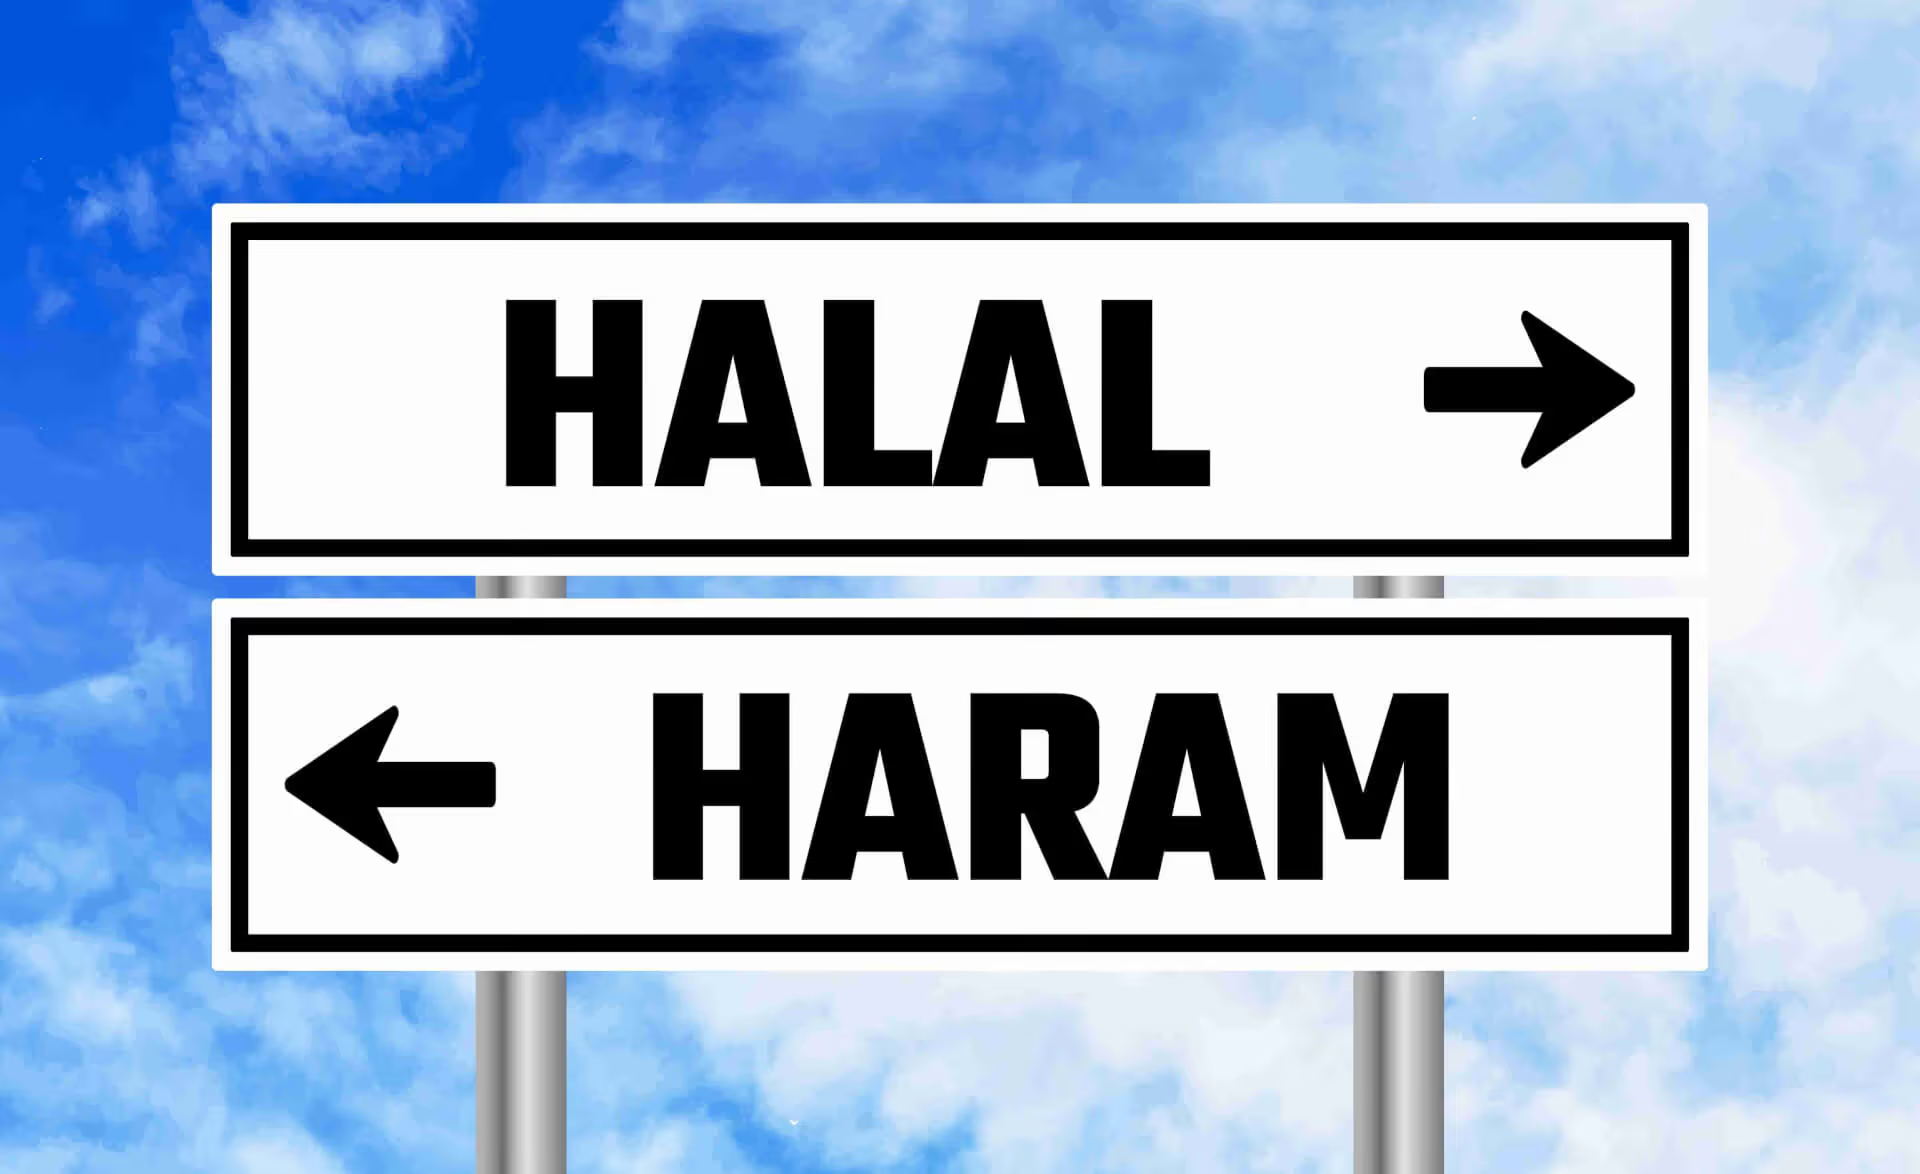
The Concepts Of Halal And Haram Explained
In order to ascertain and evaluate if investment banking is halal or haram, we need to understand the Islamic (Sharia) concepts of halal and haram.In their very basic form, halal and haram mean the following:
- halal - permissible
- haram - impermissible/prohibited
When something is deemed to be halal in Islam, it means that it meets the very specific criteria Islam sets out. Often, the concept of halal is commonly associated with the consumption of food and drink, but in reality for Muslims the concept of halal and haram permeates their daily lives, behaviours, and actions.
For example, drinking alcohol is haram, but so is engaging in dishonest or interest-based financial activities.
WHY IS HALAL AND HARAM IMPORTANT IN ISLAM?
The concepts of halal and haram are important for Muslims as they influence their daily choices, behaviours, and practices.
Let's explore these concepts and understand why they matter to Muslims.
Halal encompasses actions, behaviours, and practices that are permitted and encouraged by Islamic law (Sharia). Halal extends to various aspects of life, including business transactions, financial dealings, accounting, personal conduct, and moral and ethical considerations.
The importance of halal lies in its connection to piety and the pursuit of righteousness. Muslims strive to lead a life in accordance with Allah's commands, and adhering to the concept of halal is a means to attaining spiritual purity and fulfilment.
By consuming halal food, engaging in halal financial transactions, and following halal practices, Muslims aim to align their actions with the principles of Islam and seek the blessings of Allah.
Haram, on the other hand, means "forbidden" or "prohibited." It refers to actions, behaviours, and practices that are explicitly prohibited by Islamic law. Haram activities are considered sinful and spiritually harmful to individuals who engage in them.
Muslims avoid haram practices to maintain their spiritual well-being and to fulfill their duty of obedience to Allah. By refraining from haram actions, Muslims seek to purify their souls, develop self-discipline, and safeguard their relationship with Allah.
The Importance of Halal and Haram for Muslims:
- Morality and ethics: for Muslims, the concepts of halal and haram provide a guide and framework within which to live their lives. This framework is centred on principles of morality and ethics.
- Spiritual Connection: Halal and haram act as guiding principles for Muslims, enabling them to establish a strong spiritual connection with Allah. By adhering to halal and avoiding haram, individuals aim to cultivate righteousness and seek closeness to Allah in their daily lives.
- Personal and self-discipline: Adhering to halal and avoiding haram helps Muslims in their personal development by fostering self-discipline, self-control, and mindfulness. Consciously following the halal path means individuals can enhance their character, strengthen their faith, and develop a sense of accountability.
- Social Cohesion: The concepts of halal and haram contribute to social cohesion within the Muslim community. Shared adherence to these principles promotes unity, mutual respect, and a sense of collective responsibility among Muslims.
Islamic Finance Principles
Islamic finance principles that relate to investment banking are in place to ensure that investment banking activities are Sharia compliant.
Some of the key Islamic finance principles that would govern investment banking trading and activities include the following:
- No riba - one of the main principles to adhere to when looking for halal investment banking is ensuring there is no element of interest involved in the transaction.
- uncertainty - similarly, there should be little to no uncertainty (ghahar) and speculation.
- ambiguity - there should be no ambiguity
- Profit and loss sharing - the parties should share in any profits and losses.
- ethical - the investment activities should be ethical
Principles Of Traditional Investment Banking
Traditional investment banking operates within the framework of conventional financial systems and practices.
These systems are often interest-based. In Islamic the concept of interest (riba) is strictly prohibited. So, investment banking which relies on interest based activities is haram.
Conventional investment banking involves activities such as capital raising, mergers and acquisitions, underwriting securities, and providing financial advisory services.
Traditional investment banks typically engage in interest-based transactions, speculative investments, and may invest in sectors that are considered unethical or haram according to Islamic principles, such as alcohol, gambling, or pork-related industries.
In traditional investment banking, interest (riba) plays a significant role, as it is often earned through loans, debt instruments, and interest-bearing investments and payment options.
Additionally, derivative products, short-selling, and leveraging strategies are commonly employed in traditional investment banking practices. These activities may conflict with Islamic principles that emphasize fairness, transparency, and the avoidance of uncertainty (gharar).
The level of uncertainty and speculation within traditional investment banking can be deemed to be haram.
Sharia Compliant Halal Investment Banking
Halal investment banking, also known as Islamic investment banking or Sharia-compliant investment banking, is a specialised form of financial services that aligns with Islamic principles and guidelines.
Islamic investment banking operates within the framework of Islamic finance. These principles seek to promote ethical and socially responsible financial practices. This means there is less scope for one-sided risk and high levels of speculation. Ultimately, this leads to greater equity and fairness in business dealings.
In halal investment banking, interest-based transactions (riba) are strictly avoided. Instead, Islamic banks and financial institutions offer products and services that are structured in a way that eliminates interest, and instead, focuses on profit-sharing arrangements or partnerships.
For example, instead of charging interest on loans, Islamic banks may engage in profit-sharing agreements, lease-based contracts (Ijarah), or partnership-based arrangements (Mudarabah). What this means for the parties is that there is more fairness.
Furthermore, halal investment banking adheres to ethical investment criteria, avoiding sectors or activities that are deemed haram, such as the porn or alcohol industry.
Investments are directed towards industries that comply with Islamic principles, such as halal food, healthcare, sustainability projects, renewable energy, and ethical real estate.
The concept of risk-sharing is also emphasized in halal investment banking. Islamic financial institutions aim to distribute risks and rewards equitably among parties involved in investment activities. This principle promotes fairness, accountability, and responsible investment practices.
Key Differences Between Traditional And Halal Investment Banking
Overall, the key difference between traditional investment banking and halal investment banking lies in their underlying principles and practices.
Halal investment banking adheres to Islamic guidelines, avoiding interest-based transactions, speculative investments, and unethical industries while emphasizing risk-sharing, profit sharing, ethical investment, and fairness.
By aligning financial activities with Islamic principles, halal investment banking seeks to cater to the specific needs and values of Muslim investors.
Muslims And Investment Banking
Islamic investment banking is a growing industry. In the United Kingdom, there are many banks and financial institutions that offer halal investment banking opportunities, products and services.
For students who are currently studying economics and finance subjects, there are opportunities to seek employment and a career in Islamic investment banking firms.
However, it is important to make sure that you work with investment bankers who are familiar with the concepts of Islamic finance and halal and haram. They will guide you to investment banking services and options that are deemed to be halal under Islamic finance rules.
Qardus Limited does not give financial or investment advice.
LONDON _ A new UK-based Shariah-compliant crowdfunding platform which provides business financing to small and medium sized enterprises (SMEs) launched at the end of June.
Qardus Limited, which connects SMEs to investors, is an appointed representative of Share In Ltd, which is authorised by the Financial Conduct Authority.
Shariah-compliant crowdfunding is not a new concept in the UK, that already has platforms such as property-focused Yielders, but there are none already providing SME business financing.
“In terms of competition we would be the first to offer an Islamic business financing facility in the UK as the Islamic banks look at much larger ticket sizes,” Hassan Daher, Qardus founder and CEO told Salaam Gateway.
“In the UAE there is Beehive. Other fintechs in the UK such as Funding Circle and Iwoca only offer conventional financing facilities, not Islamic,” he added. In other regions, Kapital Boost, which was founded in 2015, was Asia’s first Islamic P2P crowdfunding platform for SMEs.
Capital at Risk. Returns are not guaranteed
July 13 2020, read the full article at Salaam Gateway: https://www.salaamgateway.com/story/uk-gets-its-first-islamic-p2p-crowdfunder-for-smes
The United Kingdom is going through a turbulent financial and economic situation. Coming out of the pandemic, navigating the financial landscape and the economy has resulted in the highest inflation we have seen in decades, alongside stagnant wages and rises in energy bills.
The cost of everything is increasing and it is ordinary people who are struggling. From the National Health Service, to the private sector, and across every community we are all feeling the pinch.
Whilst we expect the government to ensure there is sufficient funding and investment in communities, families, and industries, what is clear is that we all need to be taking steps to minimise the risk of financial losses.
Whilst the government seems more focused on climate action, decarbonisation, and reducing emissions than effective financial planning, as individuals we need to take responsibility for our own actions.
Now is the time for us to be examining out own finances and expenditure.
As we move forward into 2024 and beyond there are some key steps you can take to make sure you are in the best financial position you can be.
Get Informed
Before we move on to the steps we can take to improve our finances, we need to consider our own financial literacy.
As individuals and communities we need to prioritise learning about and understanding finance. Prepare for the future by taking the time to learn about the key principles around money and money management. Learn how interest works, and why it is deemed to be haram in Islam.
As consumers, we need to scrutinise and assess our impact on our finances and understand how we spend and save.
The more information you have the better. The worst thing you can do is bury your head in the sand.
Start by getting details of all your bank accounts, savings, direct debits and debts. Understand your incomings and outgoings and make sure you are living within your means.
One of the key principles of Islam is to live within your means. This encourages people to be mindful of how they consume and spend, and to avoid extravagance.
There are also stringent obligations to ensure that you stay away from riba (interest) and haram spending. You cannot do this properly unless you understand your finances fully.
Knowing your finances means you can avoid haram practices. Also, in order to plan effectively for the future you need to understand how your money is saved, whether it accrues interest, and how much you can save each month.
There is ample information and advice on this website to guide you along the way. In addition, technology is so advanced that these days we can check all our accounts and finances using our mobile phones. As a result, you can keep a close eye on your finances.
Focus On Sustainable And Responsible Consumption And Investing
Focusing on sustainable and responsible consumption is key for everyone, but especially Muslims who want to live in a Sharia compliant way. Islam encourages ethical and socially responsible behaviour in every area of life.
We are required to make a commitment to being sustainable and responsible. Over-consumption goes against Islamic finance principles.
Some of the best ways of achieving a more halal and sustainable level of consumption include:
- The concept of amanah
- Islam considers money and wealth to be an amanah from Allah. What this means is that Muslims act as stewards of the wealth and will be held accountable for how they use and spend it. Sharia rules guide us to use the wealth in morally and ethically sound ways, and Islamic finance provides us with the structure in which to do this. The construction of Islamic finance principles helps us to make sure we operate within Islamic principles when it comes to our finances. In personal terms, it means that we should be more considered and careful with our finances, avoiding excessive spending, and always taking care to mind our money.
- Avoiding waste
- Any kind of waste should be avoided, and this includes wasteful purchases and spending. Responsible consumption aligns with the principle of stewardship. Keep an analysis of what you spend on and how you spend and you will be able to identify and report on poor spending and then eliminate it.
- Avoiding haram but invest wisely
- As Islam prohibits actions that cause harm to others, we need to be mindful of any spending that is deemed to be haram. This includes investing in industries that are haram such as gambling, alcohol and porn industries. Instead, we should look at halal investment options and services.
- There is a huge social impact to investing in haram industries. Be mindful of where your sums are stored and being invested. The corporate world may be focused on profits, but there are socially responsible and Sharia compliant industries you can invest in. There is also increased regulation and protective policy of most investment options across the United Kingdom which means you can be assured that your money will be safe.
Think Long Term
As mentioned above, try and think long-term. When it comes to your finances, whilst it may seem like you are living from one pay day to the next, there are some small steps you can take to plan for the future. As the old saying goes - fail to prepare, prepare to fail.Planning ahead can relieve the pressure you face tomorrow. The market is fluctuating and temperamental now but it will not always be like this.
Planning ahead builds financial stability and means you can cope with emergencies when they arise. Think of the scenario of when you are much older and unable to work as hard.
Living from one pay day to the next can result in more and more people turning to debt and credit to cover their everyday expenses. Long-term financial planning helps break the cycle of debt. The UK has an ageing population, so it is even more important that we plan ahead and make the right financial decision for our future.
Here are some steps you can take to effectively plan ahead:
- Set some financial goals: these do not have to be complicated or difficult. Instead, they should be realistic. For example, one goal could be to start saving for a home.
- Create a budget: once you have a goal, go through all your financial data including incomings and outgoings. Try and track your spending to see where you can cut back and what you can do cheaper. This will help you identify any spare funds for saving. Even £5 a month will help.
- Have an emergency fund: to stop yourself from falling into debt, try your very best to have an emergency fund.
- Save and invest regularly: consistent investing, even with the tiniest amounts, can accumulate over time. When dealing with the increasing cost of living, we need to have some money set aside for emergencies.
- Ditch the debt: overspending is one of the fastest ways to end up in debt. If you are in debt there is help and support out there, so reach out and see if you can reduce your debt and lower your spending.
For Muslims, financial literacy means they can plan and prepare responsibly. It also means they can account for their zakat payments which are obligatory.
Embrace Islamic Finance Principles
Muslims are obliged to follow the Sharia rules relating to finance. For Muslims, true success comes with pleasing Allah.
Embracing Islamic finance principles is extremely important for those wanting to be compliant with Islamic rules relating to financial dealings, but also for those wanting to live and manage their money responsibly.
Islamic finance prohibits any form of interest - that includes payment of interest or receipt of it. The whole idea behind avoiding interest is that this creates a fairer society and does not burden one group more than others. Interest is seen as being rooted in unethical and irresponsible economics.
Islamic finance is based on social justice and fairness. Islam places great emphasis on ethical behaviour, through choice. This means there is an obligation on Muslims to treat all their social and economic dealings with care.
Another key concept from Islamic finance is the idea of profit and loss sharing. Sharia rules encourage profit and loss sharing arrangements. This is to ensure that both parties are treated fairly.
For Muslims looking to save costs and stay away from debt, focusing on Islamic finance rules means they can operate Islamically but also in a way that maximises their money and makes it go further.
Establish Zakat And Sadaqa
Establishing zakat and sadaqa are critically important in Islam. Zakat is an obligation upon all Muslims, whilst sadaqa is voluntary but hugely encouraged.
In order to pay your zakat you need to understand your finances fully. Calculating and paying zakat on an annual basis is essential for Muslims.
Working out your zakat requires an important wealth assessment and analysis calculation. What it means is that through the whole year you are more conscious of your spending and you are making plans for the payment of zakat.
Zakat encourages people to be aware of their financial assets and situation. This prevents the problem of not knowing how much zakat you need to pay.
Understanding the importance of zakat and sadaqa actually encourages savings throughout the year. It also helps people to budget and plan accordingly. Also, by paying zakat people are able to understand the importance of distinguishing between needs and wants in their own lives.
Sadaqa, whilst voluntary, generates a feeling of generosity, compassion and empathy. By willingly sharing our wealth with others it means we are attuned to the needs of others and can budget accordingly.
Stay Away From Debt And Interest
Now is the time to really understand and analyse your spending habits. Make more informed choices about where to spend and save your money. This encourages a more balanced and moderate lifestyle.
Managing your debt is always a good risk management strategy. If you have a credit card then try and stop using it and clear any debt you owe. Credit card debt carries high interest rates and is deemed haram.
Staying away from debt is one of the best financial decisions you can make for yourself. Debt can lead to financial strain, and negatively impacted credit scores. It also means you have overall less disposable income from jobs, and this limits you being able to set goals, save and invest for the future. This will give you greater peace of mind when preparing for the future.
Qardus Ltd do not provide financial or investment advice. It is recommended that you seek your own independent advice from a qualified professional.
Stay informed on finance